Recent Posts
Categories
Tags
Years
Rates Jumped in September: Should You Lock or Float Now?
Right now, I'm telling buyers to lock, not float. Rates have more room to go up than down, and the last six weeks showed how fast that can happen.
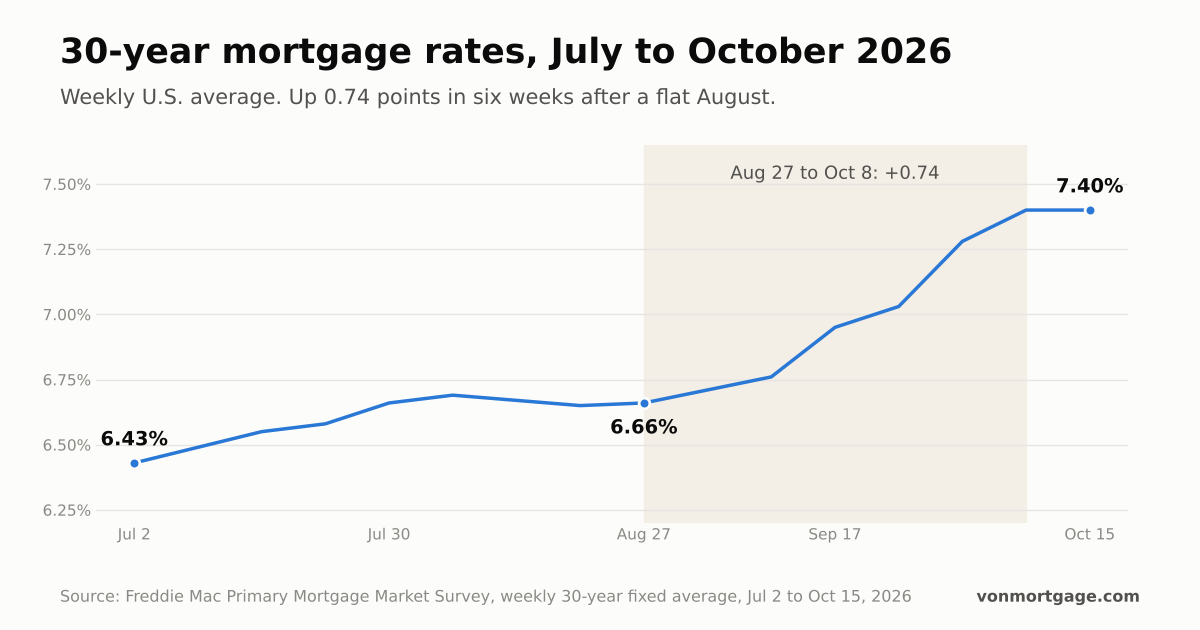
The 30-year fixed rate averaged 6.66% on August 27. By October 8 it was 7.40%, and it held there on October 15, according to Freddie Mac's Primary Mortgage Market Survey. That's 0.74 points in six weeks, after a flat August.
I'm Pete Metz, a mortgage broker at Von Mortgage in Redding, California (NMLS #260571). Here's what that move did to the buyers and sellers I'm working with, and what I'd do now. Updated October 19, 2026.
Why did rates go up so fast?
Inflation, and energy prices in particular. The September Consumer Price Index, released October 14, showed prices up 3.7% from a year earlier and 0.6% in a single month, according to the Bureau of Labor Statistics. Energy was up 20.4% over the year, and gasoline alone was up 34.2%.
Mortgage rates follow the bond market, and bond investors demand more when inflation runs hot. A month like that tells them the Federal Reserve has more work to do, not less. Our earlier post explains what a CPI report can do to your rate lock.
Who got hurt by the jump, and who didn't?
It came down to one thing: whether you were in escrow.
Buyers who had already found a home and had an accepted offer could lock their rate, and many did before the climb. Buyers who were still shopping couldn't. You can't lock a rate until you have a property under contract, so those buyers watched the rate rise with no way to stop it.
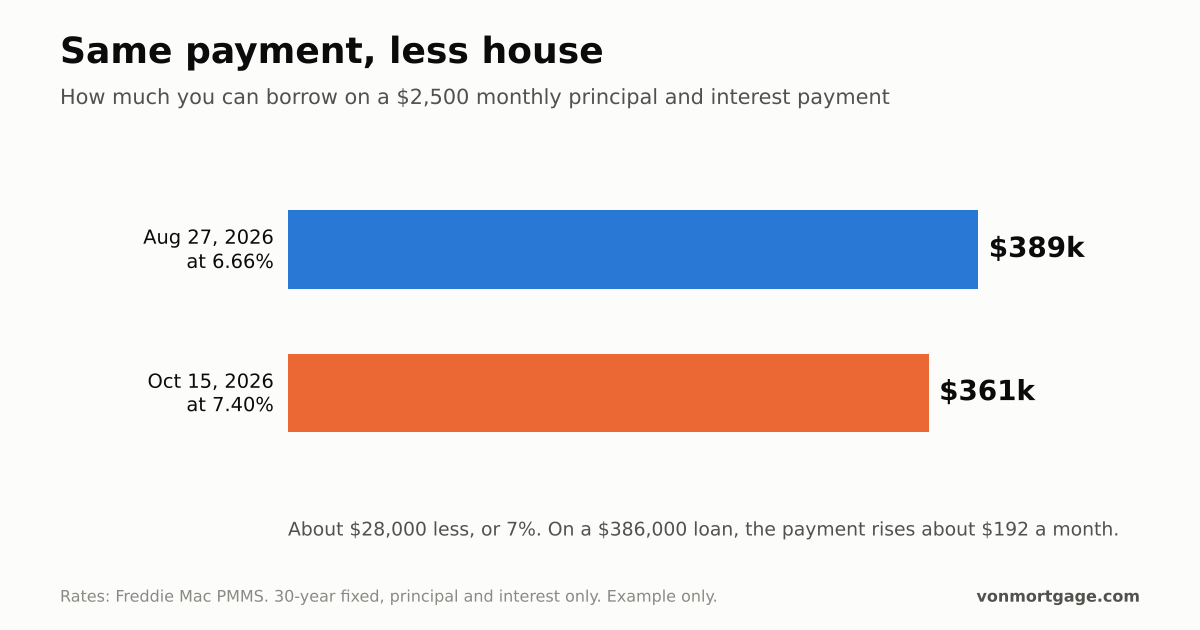
On the same $2,500 monthly principal and interest payment, a buyer could borrow about $389,000 at 6.66%. At 7.40%, the same payment covers about $361,000. That's roughly $28,000, or 7%, less house. On a $386,000 loan, it's about $192 more a month.
Nationally, the National Association of Home Builders estimated in February 2026 that each quarter-point rise in rates prices roughly 1 million to 1.4 million U.S. households out of a median-priced new home, depending on where rates start. A 0.74-point move is about three quarter-points.
Why does a rate jump help sellers who are already in escrow?
Because the buyer has more to lose by walking away. A buyer who backs out has to start over at a higher rate on the next house. Most think twice.
I'm seeing this right now in files working through repair requests. Sellers have a bit of the upper hand, but they also have more reason to make a deal work. If the sale falls through, they relist into a higher-rate market with fewer buyers who qualify at their price. That cuts both ways, and it's why repair negotiations are getting done.
Should you lock or float right now?
Lock. Today rates have more pressure to go up than down. Inflation is running hot, oil prices are pushing it, and I think there's more room for rates to rise to cool it.
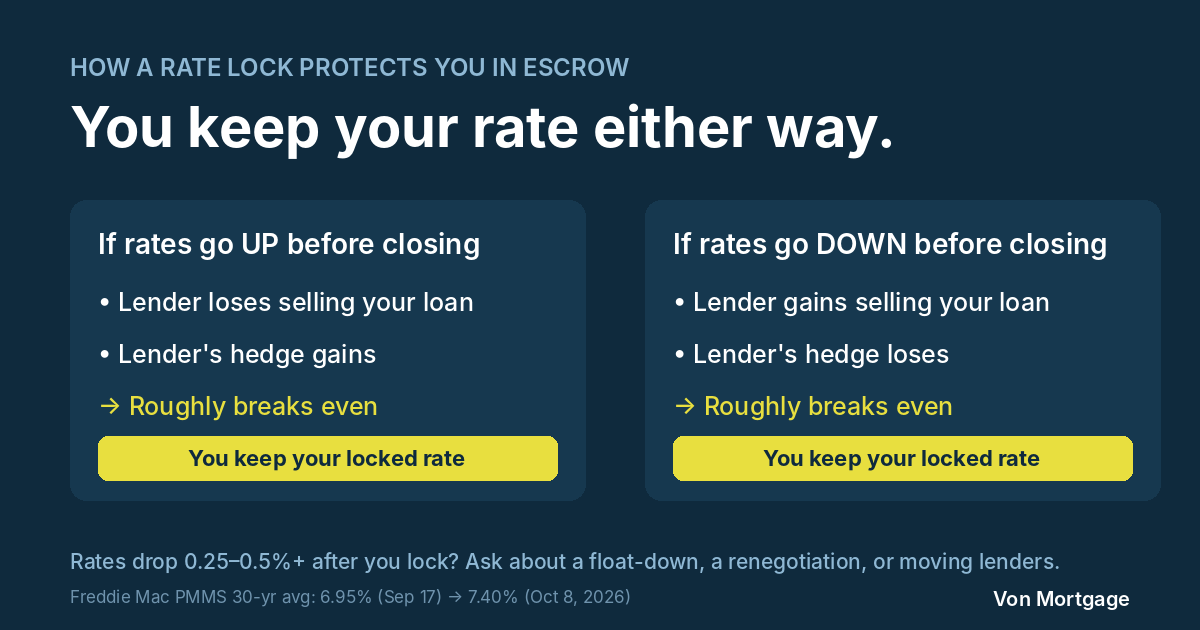
If rates drop after you lock, you aren't necessarily stuck. Many lenders offer a float-down or will renegotiate a lock if rates fall by about half a point or more. Ask about it before you lock, not after.
The part a rate headline doesn't tell you
A float-down isn't automatic. The terms vary by lender, and a small drop usually won't trigger one.
Working with a broker gives you one more option: if rates fall far enough, a broker can take your loan to a different lender. But there's a cost the industry doesn't advertise. Lenders track how many of a broker's locks actually close, called the pull-through rate. A broker below about 80% risks the relationship with that lender. A good broker will tell you honestly when moving your loan makes sense, and when the savings aren't worth it.
And my read on rates is a read, not a promise. Nobody knows where rates will be in 30 days. That's exactly why I'd rather lock a payment that works than bet on one that might.
What this means for you
If you're in escrow and haven't locked, talk to your lender this week. If you're still shopping, get pre-approved now, so you can lock the day your offer is accepted. And if you're selling, a buyer who's already locked is worth more to you than one who isn't.
If you want to see what today's rates mean for your payment, check current rates or start a quote and I'll run your numbers. If you're buying your first home, our first-time buyer page covers the rest.
Disclaimer: This information is educational and is not a commitment to lend, a loan approval, or an offer of credit. Any rates, payments, down payments or other figures shown are illustrative examples only — not quoted terms and not an offer to extend credit. Actual rates and terms depend on credit, income, property, occupancy and market conditions, and change daily. For current pricing see vonmortgage.com/rates.
Pete Metz, Mortgage Broker · NMLS #260571
Dream Big Ownership LLC dba Von Mortgage · NMLS #2592815
2777 Bechelli Lane, Redding, CA 96002 · Pete@VonMortgage.com
Equal Housing Opportunity.
 Equal Housing Lender
Join the conversation
Comments are reviewed before they appear. Have a question about your own situation? Ask Pete directly — that stays private.
No comments yet