Recent Posts
Categories
Tags
Years
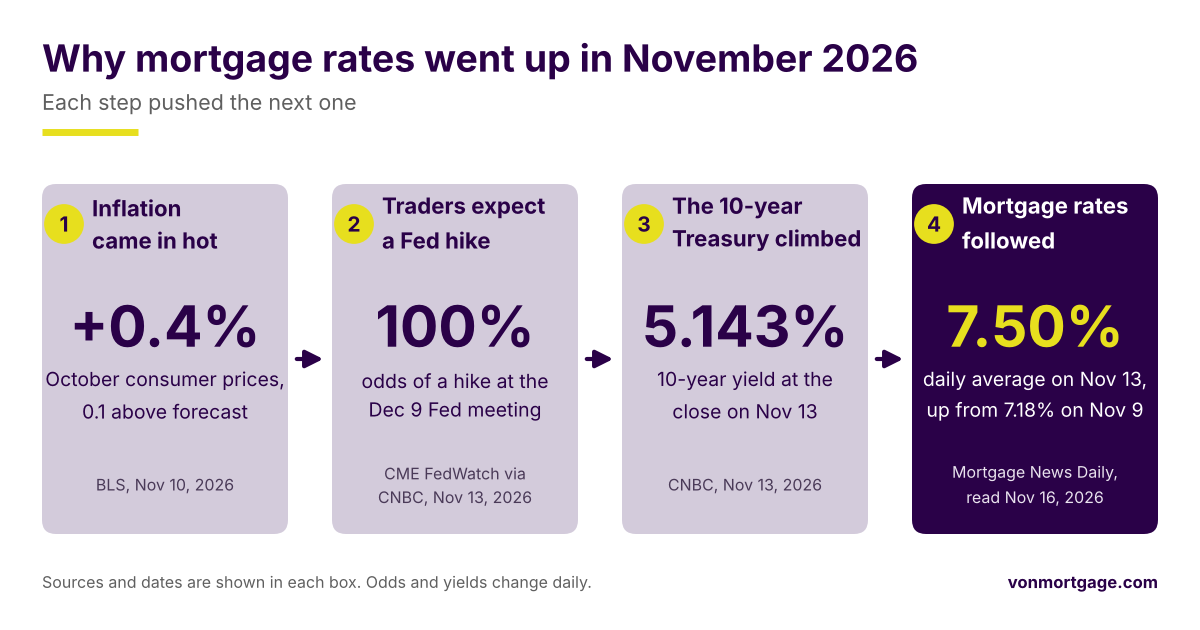
Mortgage rates are going up again. The average 30-year fixed rate went from 7.18% on Monday, November 9 to 7.50% on Friday, November 13, 2026, on Mortgage News Daily's daily index. Matthew Graham of Mortgage News Daily wrote on November 13 that three days erased most of the past five weeks of improvement.
My advice to families in Redding, California does not change in a week like this. Lock for the length of your escrow. Make sure the payment fits your budget first.
Why are mortgage rates going up again?
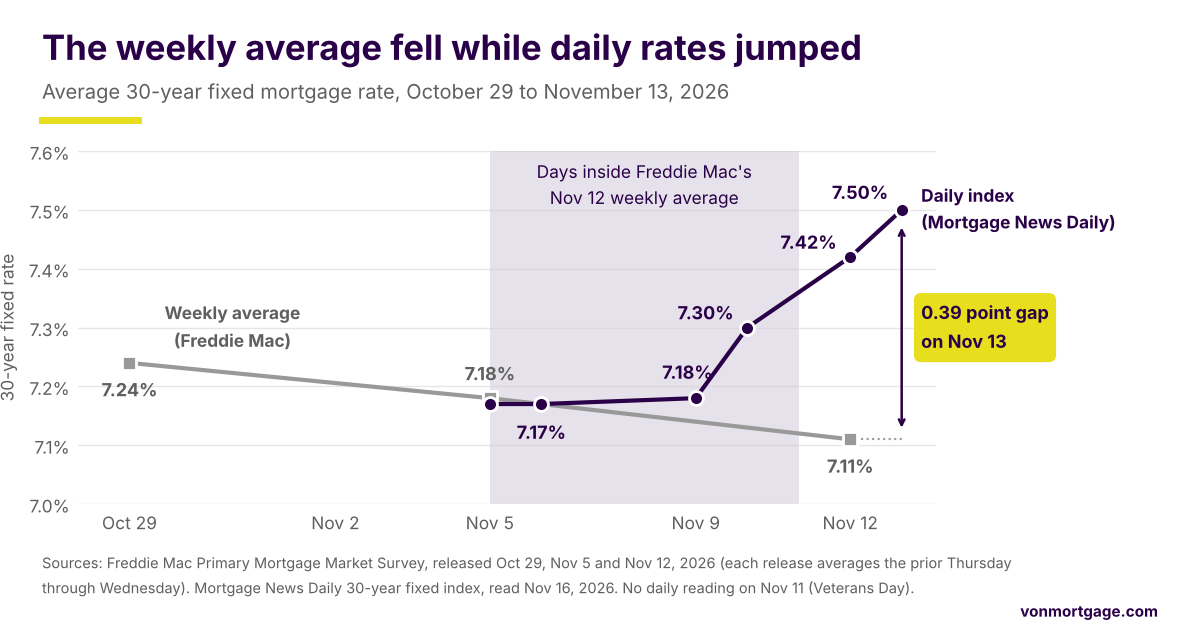
Mortgage rates are going up again because October's inflation reports came in hot and traders now expect the Fed to raise rates on December 9. That pushed the 10-year Treasury yield above 5%, and 30-year mortgage rates follow that yield. Daily rates climbed even as Freddie Mac's weekly average dipped to 7.11%.
The Consumer Price Index rose 0.4% in October. Core prices, which leave out food and energy, rose 0.3%. Each was 0.1 above the forecast (Bureau of Labor Statistics, November 10, 2026). Three days later, the wholesale price report showed prices up 6.5% from a year ago, the biggest jump since November 2022 (Bureau of Labor Statistics, November 13, 2026). Our post on how the October CPI report moved mortgage rates has the details.
The 10-year Treasury yield is the interest the U.S. government pays to borrow money for ten years. It closed at 5.143% on Friday, November 13 (CNBC, November 13, 2026). Early Monday, November 16, it eased to 5.131% (CNBC, November 16, 2026).
Why did the weekly average fall while daily rates jumped?
The weekly average fell because it covers a full week, and most of that week came before the jump. Freddie Mac averages the rates on loan applications from Thursday through the next Wednesday, then publishes on Thursday (Freddie Mac, Primary Mortgage Market Survey page, read November 16, 2026).
The November 12 average of 7.11% covered November 5 through November 11. Only one day of the jump, November 10, fell inside that week. The daily index kept climbing after the survey closed. It hit 7.42% on November 12 and 7.50% on November 13 (Mortgage News Daily). By Friday the daily number sat 0.39 points above the weekly one.
Will the Fed raise rates in December, and will mortgage rates follow?
Traders expect a hike, but mortgage rates do not move point for point with the Fed. On November 13, 2026, the CME FedWatch tool showed 100% odds of a hike at the December 9 meeting, with a quarter point the most likely size at 89% (CNBC, November 13, 2026). Early Monday, November 16, it eased to 5.131% (CNBC, November 16, 2026).
The Fed sets a short-term rate. A 30-year mortgage is priced off the 10-year Treasury yield, and that yield has already moved up because a hike is expected. So some of December's news may already be in today's rates.
The Fed held its rate steady in October. See what the October Fed hold meant for mortgage rates and how Fed meetings move mortgage rates.
Will mortgage rates go up this week?
Nobody can know for sure. A Fed speech, two reports and the Fed's meeting notes could move rates either way this week. Strong numbers tend to push rates up. Weak numbers tend to pull them down.
| Day | What comes out | Why it matters |
|---|---|---|
| Mon, Nov 16 | Fed Chair Kevin Warsh spoke (9 AM Pacific) | Watched for hints about December |
| Tue, Nov 17 | October retail sales | Shows how much families spend |
| Wed, Nov 18 | Housing starts, and notes from the Fed's October 27 to 28 meeting (11 AM Pacific) | Shows the Fed's thinking in October |
| Thu, Nov 19 | Freddie Mac weekly average | First week that covers the jump |
What should Redding families do if they're buying or refinancing right now?
Lock for the length of your escrow, and make sure the payment fits your budget today. That is what I tell families in Redding, California. Escrow is the time between your accepted offer and closing day. A 45-day escrow gets a 45-day lock. Our post on what a mortgage rate lock is explains how a lock works.
Don't try to time the market. Waiting to save an eighth of a point is a gamble. Last week the daily average rose 0.32 points from Monday to Friday.
If your lock needs more time, extend it no more than 30 days at a time.
Affordability comes first. The payment has to fit your budget at the rate you can get now. Refinancing later is a bonus, not the plan. A buydown is money paid up front to lower your rate, for the first few years (temporary) or for the whole loan (permanent). Buydowns can help, but only after the full payment fits. Real estate is a long-term game.
If you're in escrow this week, my advice is simple. I always recommend locking.
What else are families asking about mortgage rates?
Families also ask what December could bring, why mortgage rates track the 10-year Treasury, and whether to lock now. Here are the short answers.
Will mortgage rates go up in December?
Nobody knows yet. Traders expect a Fed hike on December 9, and the 10-year Treasury yield has already climbed above 5% because of it (CNBC, November 13, 2026). Where mortgage rates go in December depends on the reports that come out between now and then.
Why do mortgage rates follow the 10-year Treasury?
Mortgage rates follow the 10-year Treasury because the same investors buy both. Mortgages are bundled into bonds, and those bonds compete with the 10-year Treasury for investors' money. When the Treasury pays more, mortgage bonds have to pay more too. That shows up as a higher mortgage rate.
Should I lock my rate now or wait?
Lock when your lock period covers your closing date and the payment fits your budget. Waiting is a bet that can go either way. See whether to lock or float when rates jump.
Want to see your payment at this week's pricing? Send me your numbers and I'll run them. Not ready yet? Rate Watch lets you keep an eye on rates.
Pete Metz, mortgage broker at Von Mortgage in Redding, California, NMLS #260571.
Disclaimer: This information is educational and is not a commitment to lend, a loan approval, or an offer of credit. Any rates, payments, down payments or other figures shown are illustrative examples only, not quoted terms and not an offer to extend credit. Actual rates and terms depend on credit, income, property, occupancy and market conditions, and change daily. For current pricing see vonmortgage.com/rates.
Pete Metz NMLS #260571
Dream Big Ownership LLC dba Von Mortgage Company NMLS #2592815
CA CFL license 60DBO-195824
(530) 221-7700 · 2777 Bechelli Lane, Redding, CA 96002
Equal Housing Opportunity.
 Equal Housing Opportunity
Join the conversation
Comments are reviewed before they appear. Have a question about your own situation? Ask Pete directly — that stays private.
No comments yet