Recent Posts
Categories
Tags
Years
The October CPI report, released by the Bureau of Labor Statistics on November 10, 2026, showed prices up 0.4% for the month and core CPI up 0.3%. CPI, the Consumer Price Index, is a monthly measure of what families pay for goods and services. Core CPI leaves out food and energy, the prices that jump around the most. Mortgage rates follow bond yields, the interest rates on bonds. Bond markets react to inflation surprises. Hotter than expected usually pushes rates up. Cooler usually lets them ease. One report rarely changes the trend by itself.
Rates are up this morning. By mid-morning, the 10-year Treasury yield was up about 0.15 percentage points, and mortgage bond prices were down about 0.53 points. Here's what that means for you. When mortgage bond prices drop by 0.53, the same rate you could have gotten yesterday now costs about 0.53% of your loan amount more today. On a $400,000 loan, that's about $2,120 more for the exact same rate.
What did the October CPI report show?
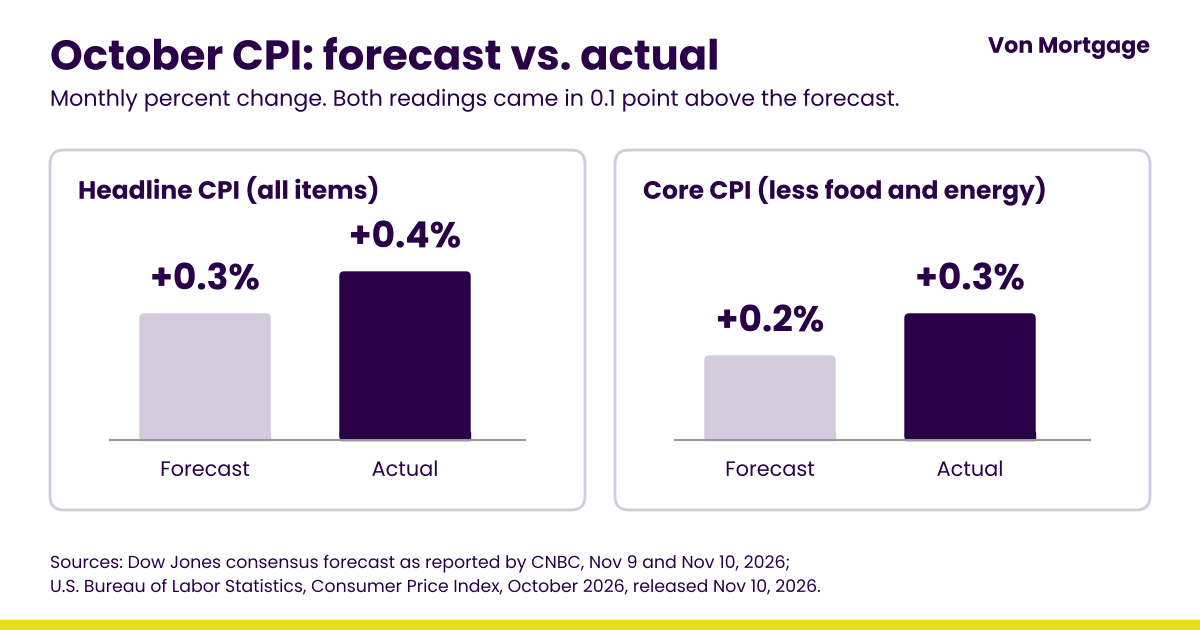
Prices rose 0.4% in October after rising 0.6% in September, according to the BLS Consumer Price Index release of November 10, 2026. Core CPI, which leaves out food and energy, rose 0.3%, the same as in September and August. Both came in 0.1 point above the Dow Jones consensus forecast of 0.3% and 0.2%, as reported by CNBC on November 10, 2026. A consensus forecast is the typical guess from economists.
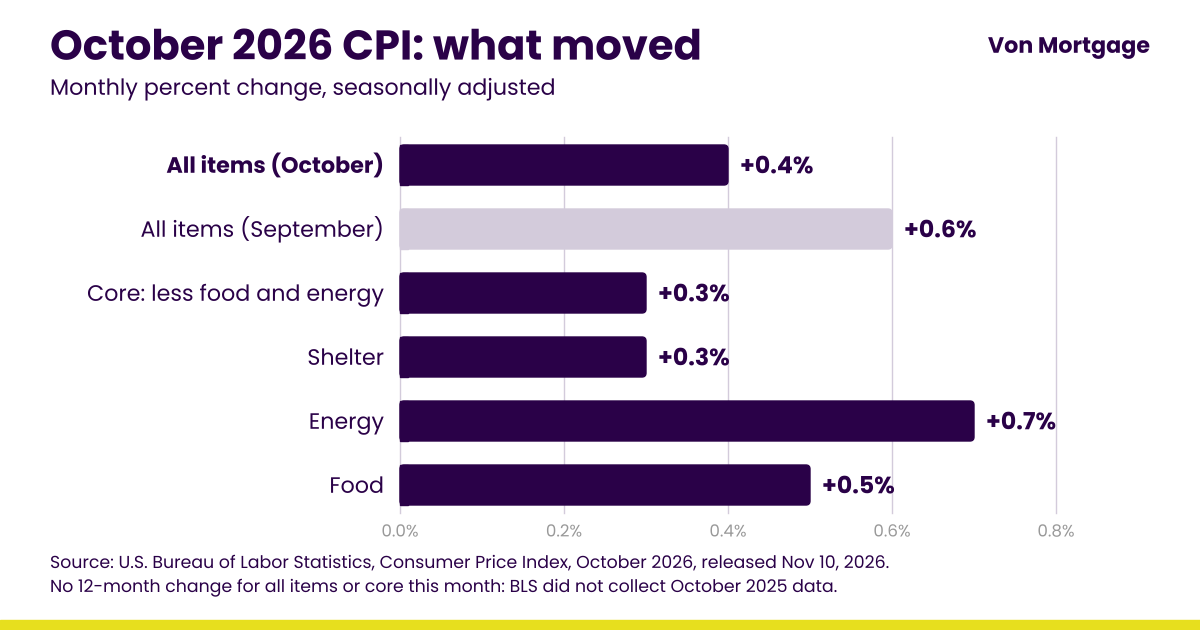
Shelter rose 0.3% in October, and BLS said it accounted for over thirty percent of the monthly all items increase. That was in a report that came in 0.1 point hotter than the consensus on both headline CPI, the overall number, and core. Housing costs are the biggest single driver of the monthly increase, and they're slow to cool.
Owners' equivalent rent is the biggest piece of shelter. That is what BLS estimates owners would pay to rent their own home. Rent is next, then lodging away from home, which is hotels and motels. Owners' equivalent rent rose 0.3% in October. Rent rose 0.2%. Lodging away from home rose 0.6%, down from 2.0% in September.
Energy rose 0.7%, far less than September's 5.2%. Food rose 0.5%.
This report is different from most because there is no year-over-year comparison. BLS did not collect October 2025 prices during the government shutdown, so the only 12-month changes it published were for single items: gasoline, new vehicles and used cars. If you see an annual headline figure for October, it did not come from the BLS release.
How does the CPI report affect mortgage rates?
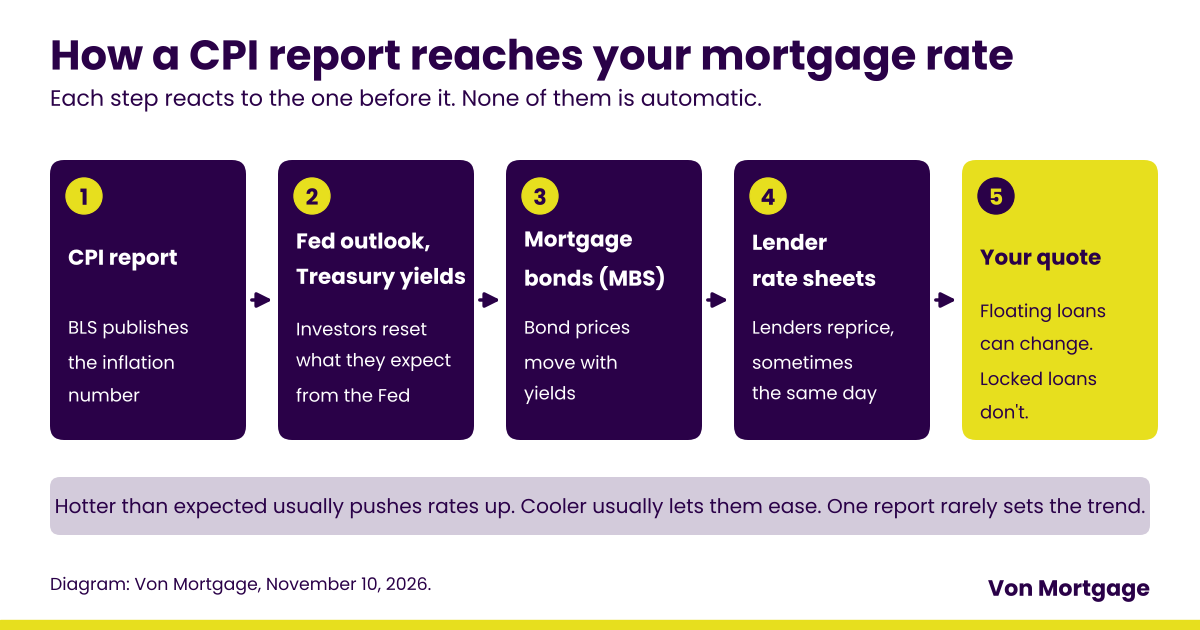
The CPI report affects mortgage rates through the bond market. A hotter-than-expected inflation reading usually pushes bond yields and mortgage rates up, and a cooler one lets them ease. When inflation comes in above the forecast, investors expect the Fed, the Federal Reserve, to keep money tighter. They want higher yields on Treasuries, the interest rates on United States government bonds. Mortgage-backed securities are bonds made by bundling home loans together, and they trade alongside Treasuries. When their prices fall, lenders put out new rate sheets, the price lists used to set your quote, with higher rates or higher costs. That is how a number published at 5:30 in the morning Pacific time can reach a quote by lunch.
The surprise matters more than the number itself. Right after the release, the 10-year Treasury yield rose more than 7 basis points, or 0.07 percentage points, to 4.938%, according to CNBC. Yields were already climbing before the release, after a speech by Fed Governor Christopher Waller, so CPI does not get credit for the whole move.
A hot report does not always raise a family's quote. Some of the move may already be priced in, meaning investors already expected it. A locked loan, with a guaranteed rate, does not change. A floating loan still moves with the market.
Do mortgage rates go up with inflation?
Usually, yes. Investors who buy mortgage bonds get paid back in fixed dollars over many years. Inflation makes those dollars worth less, so they want a higher rate when inflation runs hot. Freddie Mac's Primary Mortgage Market Survey, a weekly rate average, for November 5, 2026 put the average 30-year fixed rate at 7.18%, compared with 6.22% a year earlier.
The link is not exact. Rates also move week to week on jobs, Fed talk and bond demand, and the same survey had the 30-year at 7.24% the week before. I covered the Fed's preferred inflation measure in how PCE inflation affects mortgage rates.
What does this mean if you're buying or refinancing in Redding?
If your loan is locked, today's report changed nothing for you. If you are floating, your quote can move with the market in either direction. On a home here in Shasta County, I'd rather a family decide based on whether the payment works than on a guess about the next report. You can check today's mortgage rates against your own numbers any time.
Should you lock your rate after a CPI report?
If you're under contract, the payment works and you're happy with the home, I normally recommend locking. I don't like gambling on lock versus float, and I wouldn't try to time the market for an eighth of a point. My team walks every family through the lock policy, including renegotiation if rates get significantly better, about a quarter to half a percent.
The timing details are in how the CPI report affects your rate lock. If locks are new to you, start with what a mortgage rate lock is and whether to lock or float when rates jump.
What's next for mortgage rates this month?
Here's what's on the calendar. None of it tells us where rates will go.
- Wednesday, November 11: Veterans Day, a federal holiday.
- Thursday, November 12: Freddie Mac's next weekly rate survey. Its window runs November 5 through 11, so it only partly reflects today's report.
- Friday, November 13: the Producer Price Index, or PPI, which tracks wholesale prices paid by companies.
- December 8 and 9: the Fed meets. CNBC reported on November 10, 2026 that markets have largely priced in a quarter-point hike, based on CME Group's FedWatch, a tool that shows what traders think the Fed will do next.
The next CPI report comes out Thursday, December 10, 2026, the day after that meeting ends. Two related reads: how the jobs report affects mortgage rates and what a Fed hold means for mortgage rates.
What else do families ask about CPI and mortgage rates?
Are mortgage rates linked to inflation?
Yes. Mortgage rates tend to rise when inflation rises and ease when it cools. That is because the investors who fund mortgages want a return above inflation. The link runs through bond yields, so it shows up more reliably over weeks and months than on any single day.
Does the CPI report change mortgage rates the same day?
It can. Lenders set rate sheets each morning and can change them during the day when mortgage bonds move sharply. A loan that is already locked does not change. A floating loan can.
What is core CPI?
Core CPI is the Consumer Price Index with food and energy prices removed. Those two categories swing the most from month to month, so the Fed and bond investors watch core for the underlying trend. Core CPI rose 0.3% in October 2026, according to BLS.
Will mortgage rates go down after this report?
Nobody knows, and I won't guess. Watch the Freddie Mac survey on November 12, the Producer Price Index on November 13 and the Fed meeting on December 8 and 9. Cooler readings would give rates room to ease. Hotter ones would work against that.
Why is there no 12-month CPI number this month?
Because BLS has no October 2025 prices to compare against. The agency did not collect survey data that month during the government shutdown, and it said it cannot publish 12-month changes for October 2026 where that data is missing.
If you're floating and want to see where your numbers land today, send me your scenario and I'll run it. No pressure to lock.
Disclaimer: This information is educational and is not a commitment to lend, a loan approval, or an offer of credit. Any rates, payments, down payments or other figures shown are illustrative examples only, not quoted terms and not an offer to extend credit. Actual rates and terms depend on credit, income, property, occupancy and market conditions, and change daily. For current pricing see vonmortgage.com/rates.
Pete Metz NMLS #260571
Dream Big Ownership LLC dba Von Mortgage Company NMLS #2592815
CA CFL license 60DBO-195824
(530) 221-7700 · 2777 Bechelli Lane, Redding, CA 96002
Equal Housing Opportunity.
 Equal Housing Opportunity
Join the conversation
Comments are reviewed before they appear. Have a question about your own situation? Ask Pete directly — that stays private.
No comments yet