Recent Posts
Categories
Tags
Years
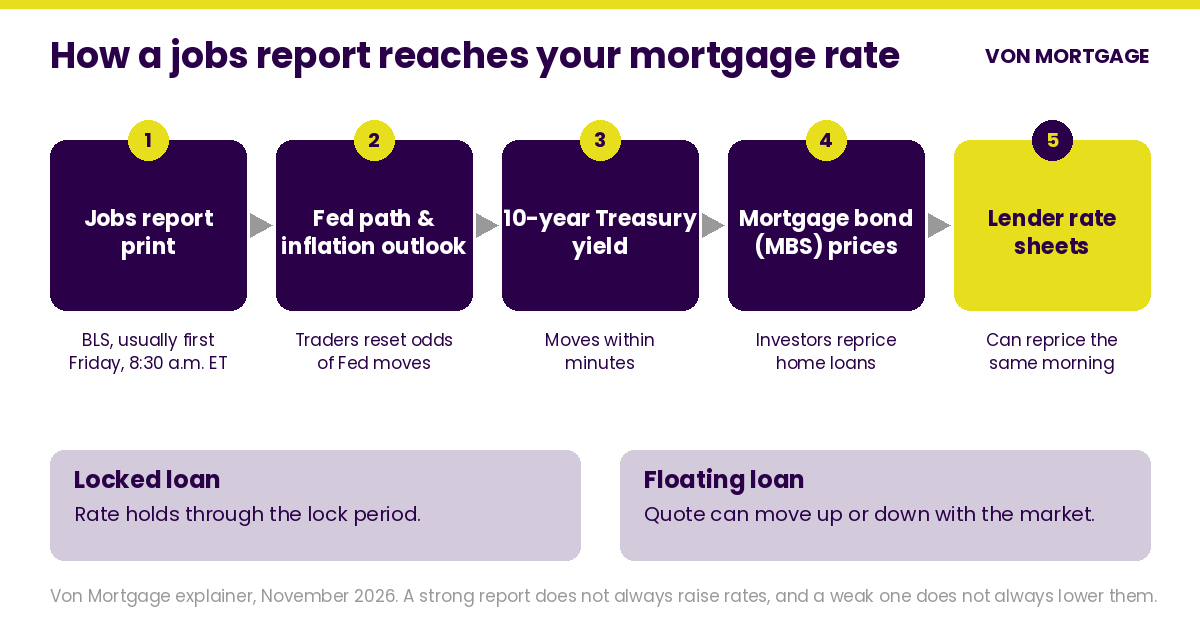
The monthly jobs report can affect mortgage rates through the bond market. Strong hiring or faster wage growth can lift inflation expectations and the 10-year Treasury yield, and lenders can reprice mortgages higher the same morning. Soft hiring can pull yields down. A locked rate stays put. If you're floating, check a live quote after a big report.
The 165,000 jobs print came in higher than the estimate, which is normally bad for bonds. This time the AI and tech selloff pulled money into longer-term bonds (the 10-year) and mortgage-backed securities (MBS), so rates have actually improved about a quarter to half a percent.
Updated November 6, 2026.
The jobs report is the Employment Situation release from the U.S. Bureau of Labor Statistics. It usually comes out the first Friday of the month at 8:30 a.m. Eastern. The Federal Reserve doesn't set your mortgage rate. The bond market does, and this report is one of the few that can affect it within minutes.
What numbers in the jobs report matter for rates?
Four numbers do most of the work: payrolls, the unemployment rate, average hourly earnings, and revisions to earlier months. Payrolls is the count of jobs added. The unemployment rate shows how much slack is left. Wages matter because pay growth can feed inflation. Revisions show whether the last two months were stronger or weaker than first reported.
Bond traders compare each number to the forecast. A big beat or miss is what can affect yields.
Why does a strong jobs report sometimes push mortgage rates up?
Strong hiring signals an economy that could keep inflation from cooling, so investors expect the Fed to hold rates higher for longer. Bond investors then want a higher yield on 10-year Treasuries and on the mortgage-backed securities (MBS) that fund home loans. When those bond prices fall, lender rate sheets tend to move up.
It isn't automatic. If the market already expected a strong number, or other parts of the report look weak, yields can barely move or even fall.
Do mortgage rates follow the Fed or the jobs report?
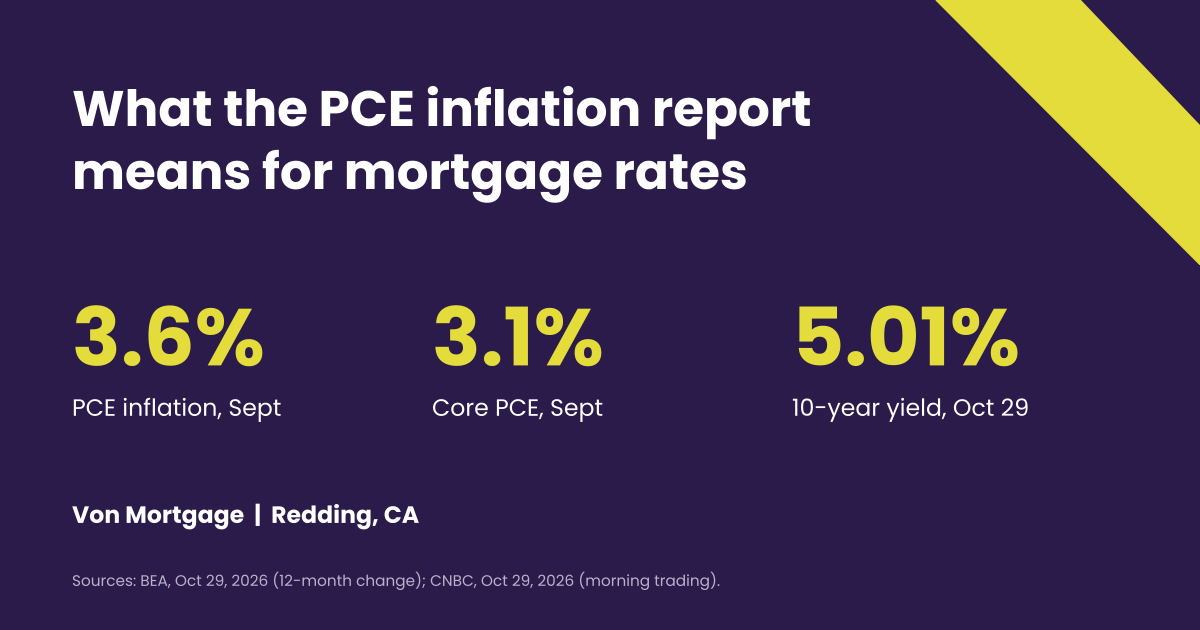
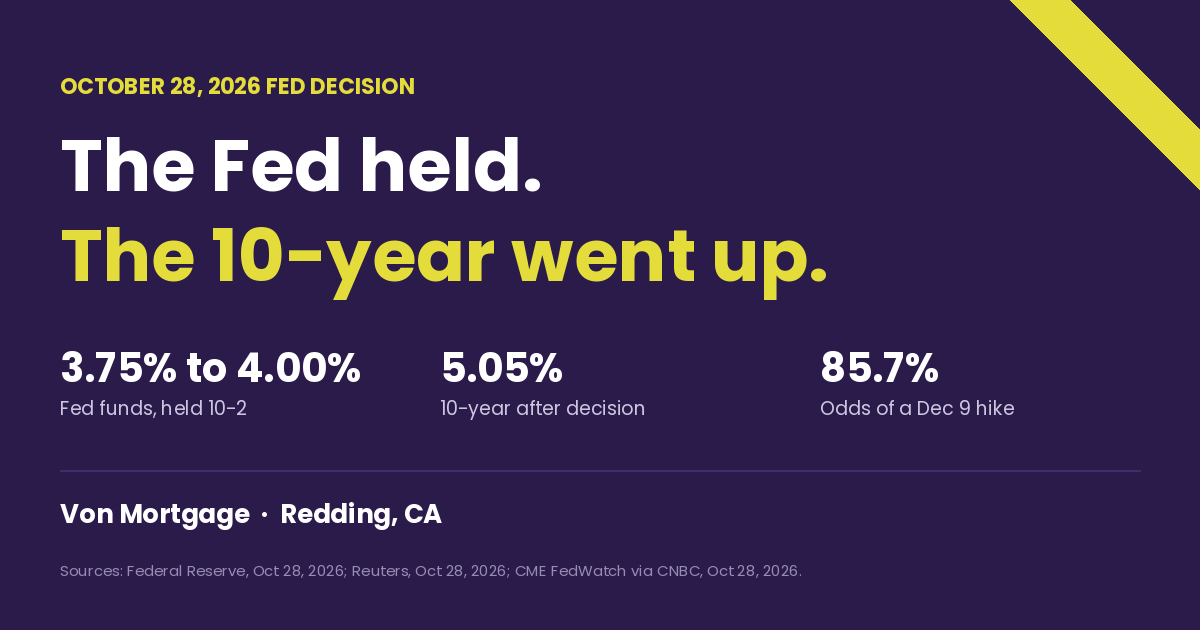
Mortgage rates follow the bond market, and the bond market reacts to both. The Fed sets a short-term overnight rate. A 30-year mortgage is priced off longer-term bonds, which move on what investors think the Fed and inflation will do next. The jobs report changes that outlook. So does inflation data, which is why PCE inflation can affect mortgage rates too, and why a Fed hold doesn't freeze mortgage rates.
What did the October 2026 jobs report show?
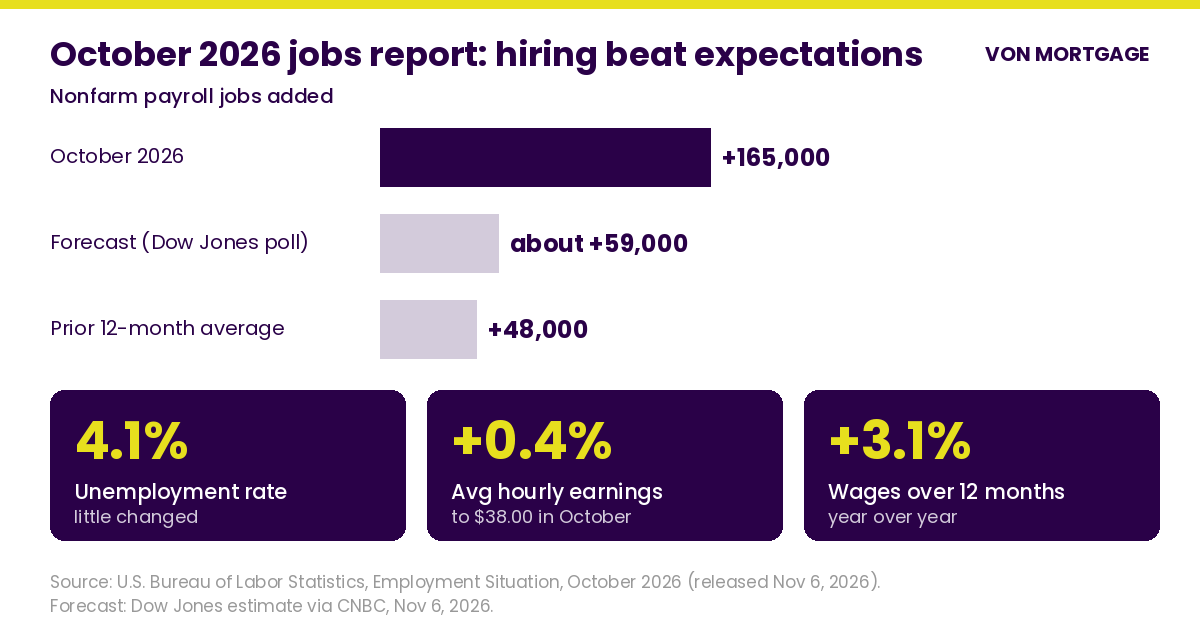
Employers added 165,000 jobs in October, far more than forecast, according to the BLS Employment Situation report released November 6, 2026. Economists polled by Dow Jones expected about 59,000, CNBC reported. Over the prior 12 months, payrolls grew an average of 48,000 a month.
- Unemployment rate: 4.1%, little changed. The forecast was about 4.2%.
- Average hourly earnings: up 0.4% to $38.00, and up 3.1% over 12 months.
- Revisions: August and September were revised up a combined 84,000 jobs.
- Biggest gains: professional and business services (+70,000), health care (+42,000), transportation and warehousing (+25,000), manufacturing (+19,000).
- Soft spot: leisure and hospitality lost 13,000 jobs.
Bonds reacted. The 10-year Treasury yield rose more than 4 basis points to about 4.88% on the morning of November 6, 2026, CNBC reported. A basis point is one hundredth of a percentage point. CNBC also reported that CME FedWatch odds of a Fed rate hike at the December 9 meeting rose to more than 76%, from more than 66% the day before.
Yes, the odds favor a rate hike, but if the stock market keeps declining and we keep seeing a sell-off, it's going to be really hard for the Fed to raise interest rates with recession concerns. My take is they will probably be very cautious about raising rates if stocks keep falling. It's something to watch over the next 30 days.
Freddie Mac's Primary Mortgage Market Survey for November 5, 2026, released before the report, put the 30-year fixed average at 7.18% (down from 7.24%) and the 15-year at 6.57%. That survey doesn't include this report. The next one comes out November 12. For pricing after the print, check today's mortgage rates or ask for a live quote.
Should families lock before or after the jobs report?
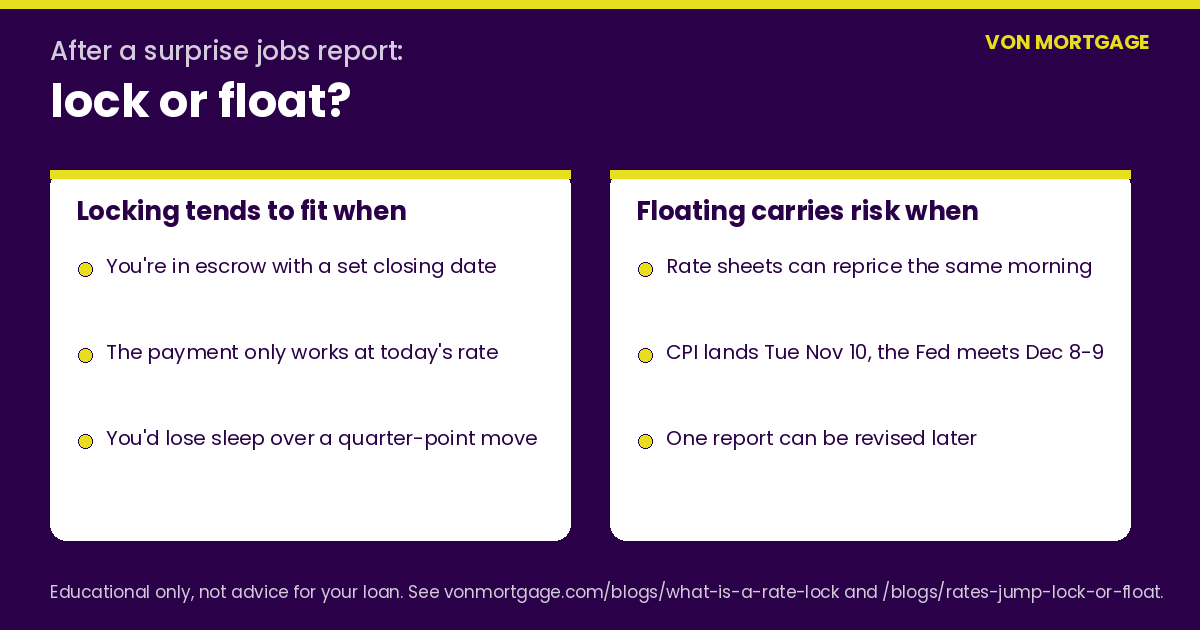
If you're under contract and today's payment works, locking before a scheduled report takes the jobs-day risk off the table. After a surprise print, the question is whether you can live with the new number. Nobody knows whether rates will be higher or lower next week, including me.
When we get a jobs surprise like this morning, I look closely at the bond market. Bonds barely moved today, which shows real strength — money is coming out of stocks into longer-term securities — so right now we're cautiously floating and watching bonds minute by minute. Even so, I normally recommend locking once a purchase goes under contract. Make sure you can afford the payment and you're happy with the home; I don't like gambling on float versus lock. We'll also walk you through the lock policy and renegotiation if rates get significantly better, and that's what I recommend.
I don't try to time the market for an eighth of a point. The home and the payment have to fit first. As an example, on a $400,000, 30-year loan, the gap between 7.25% and 7.125% is about $34 a month in principal and interest, roughly $2,729 versus $2,695. That's real money. It isn't worth losing the house over.
For the lock policy and renegotiation if rates get significantly better after you lock (including float-downs of about a quarter to half a percent), see what a rate lock is and how it works. Then read lock or float when rates jump.
Can one jobs report tell you where mortgage rates are headed?
No. One month of jobs data is noisy, and it gets revised. This report alone revised the two prior months by 84,000 jobs.
The same report also had softer spots. The number of workers in part-time jobs for economic reasons rose 339,000 to 4.8 million, and 7.1 million were unemployed, per the BLS. Markets can reverse a jobs-day move within days, especially with inflation data close behind.
The first thing I want to say is about the birth-death model that comes out every month in the jobs report. That model estimates jobs from businesses opening and closing that the survey can't catch yet — new firms take months to show up on the sample frame — so BLS uses a statistical forecast on top of the survey. October's net birth-death forecast was 412,000 jobs (not seasonally adjusted), and that number can swing a lot by month; it's a model, not a hard count, and it's hard to get exactly right, especially when the economy turns. Healthcare added 42,000 jobs (private education and health services were up 53,000). Leisure and hospitality lost 13,000. With that mix — and with the birth-death piece in the background — we got 165,000 new jobs versus a Wall Street estimate around 59,000 (not the 65,000 some were saying). August and September were also revised up a combined 84,000, which was a huge surprise and fits the strength we're seeing in the bond market right now. My take is the jobs report can sometimes look way off or less reliable than the headline suggests because so much of it rests on that birth-death model.
What comes next on the calendar?
The next big test is the October Consumer Price Index from the BLS on Tuesday, November 10, at 8:30 a.m. Eastern. Here's how a CPI report affects your rate lock. The Fed meets December 8 and 9. The next jobs report comes out Friday, December 4, at 8:30 a.m. Eastern.
What does the jobs report mean for your monthly payment?
For most families, very little on its own. A jobs-day move usually shifts a quote by a small amount, and your payment depends far more on price, down payment, taxes and insurance. If you're floating, ask for an updated quote before you decide anything. If you're shopping, build your budget on a payment you can carry at today's rates.
Von Mortgage is a mortgage broker in Redding, California. Send me your price range and down payment and I'll run the real numbers for your situation. Get a quote.
---
Disclaimer: This information is educational and is not a commitment to lend, a loan approval, or an offer of credit. Any rates, payments, down payments or other figures shown are illustrative examples only, not quoted terms and not an offer to extend credit. Actual rates and terms depend on credit, income, property, occupancy and market conditions, and change daily. For current pricing see vonmortgage.com/rates.
Pete Metz, Mortgage Broker · NMLS #260571
Dream Big Ownership LLC dba Von Mortgage Company · NMLS #2592815
Loans made or arranged pursuant to a California Financing Law license, #60DBO-195824.
2777 Bechelli Lane, Redding, CA 96002 · (530) 221-7700 · Pete@VonMortgage.com
Equal Housing Opportunity.
<!-- FAQ JSON-LD schema section -->
<script type="application/ld+json">{"@context": "https://schema.org","@graph": [{"@type": "BlogPosting","@id": "https://www.vonmortgage.com/blogs/how-jobs-report-affects-mortgage-rates#article","mainEntityOfPage": {"@type": "WebPage","@id": "https://www.vonmortgage.com/blogs/how-jobs-report-affects-mortgage-rates"},"headline": "How Does the Jobs Report Affect Mortgage Rates? October 2026 Numbers","description": "How the October 2026 jobs report can affect mortgage rates through Treasuries and MBS, what payrolls and wages mean for families, and when to lock or float.","image": "https://www.vonmortgage.com/_emdash/api/media/file/01M6RMBHWZ5S4CF0CB6GF181J2.png","datePublished": "2026-11-06T12:00:00-08:00","dateModified": "2026-11-06T09:55:00-08:00","articleSection": "Weekly Updates","keywords": "market-update, mortgage-rates, rate-lock, jobs-report","inLanguage": "en-US","author": {"@id": "https://www.vonmortgage.com/#pete-metz"},"publisher": {"@id": "https://www.vonmortgage.com/#organization"}},{"@type": "Person","@id": "https://www.vonmortgage.com/#pete-metz","name": "Pete Metz","jobTitle": "Mortgage Broker and Owner","identifier": "NMLS #260571","url": "https://www.vonmortgage.com/team","email": "Pete@VonMortgage.com","worksFor": {"@id": "https://www.vonmortgage.com/#organization"}},{"@type": "MortgageBroker","@id": "https://www.vonmortgage.com/#organization","name": "Von Mortgage","legalName": "Dream Big Ownership LLC","identifier": "NMLS #2592815","url": "https://www.vonmortgage.com","email": "Pete@VonMortgage.com","telephone": "+1-530-221-7700","address": {"@type": "PostalAddress","streetAddress": "2777 Bechelli Lane","addressLocality": "Redding","addressRegion": "CA","postalCode": "96002","addressCountry": "US"}},{"@type": "FAQPage","mainEntity": [{"@type": "Question","name": "What numbers in the jobs report matter for rates?","acceptedAnswer": {"@type": "Answer","text": "Four numbers do most of the work: payrolls, the unemployment rate, average hourly earnings, and revisions to earlier months. Payrolls is the count of jobs added. The unemployment rate shows how much slack is left. Wages matter because pay growth can feed inflation."}},{"@type": "Question","name": "Why does a strong jobs report sometimes push mortgage rates up?","acceptedAnswer": {"@type": "Answer","text": "Strong hiring signals an economy that could keep inflation from cooling, so investors expect the Fed to hold rates higher for longer. Bond investors then want a higher yield on 10-year Treasuries and on the mortgage-backed securities (MBS) that fund home loans."}},{"@type": "Question","name": "Do mortgage rates follow the Fed or the jobs report?","acceptedAnswer": {"@type": "Answer","text": "Mortgage rates follow the bond market, and the bond market reacts to both. The Fed sets a short-term overnight rate. A 30-year mortgage is priced off longer-term bonds, which move on what investors think the Fed and inflation will do next."}},{"@type": "Question","name": "What did the October 2026 jobs report show?","acceptedAnswer": {"@type": "Answer","text": "Employers added 165,000 jobs in October, far more than forecast, according to the BLS Employment Situation report released November 6, 2026. Economists polled by Dow Jones expected about 59,000, CNBC reported. Over the prior 12 months, payrolls grew an average of 48,000 a month."}},{"@type": "Question","name": "Should families lock before or after the jobs report?","acceptedAnswer": {"@type": "Answer","text": "If you're under contract and today's payment works, locking before a scheduled report takes the jobs-day risk off the table. After a surprise print I look at the bond market; when bonds hold up we may cautiously float and watch. I typically recommend locking once a purchase goes under contract if the payment fits, and we walk through lock renegotiation if rates get significantly better."}},{"@type": "Question","name": "What comes next on the calendar?","acceptedAnswer": {"@type": "Answer","text": "The next big test is the October Consumer Price Index from the BLS on Tuesday, November 10, at 8:30 a.m. Eastern. The Fed meets December 8 and 9. The next jobs report comes out Friday, December 4, at 8:30 a.m. Eastern."}}]}]}</script>
 Equal Housing Opportunity
Join the conversation
Comments are reviewed before they appear. Have a question about your own situation? Ask Pete directly — that stays private.
No comments yet