Recent Posts
Categories
Tags
Years
The fastest way to improve your credit score for a mortgage is usually to pay down credit card balances before your lender pulls your credit. The slow way matters even more: pay every bill on time.
I've closed loans for families with scores from 506 to 850 and above. So I don't treat a score as a pass or a fail. It's a number we can often move before you buy. At Von Mortgage in Redding, California, we look at what will move your score before you apply. The sources below were checked on November 14, 2026.
How do you improve your credit score for a mortgage?
Paying down credit card balances is usually the fastest way to improve your credit score for a mortgage, because how much of your limit you use counts heavily. Pay on time, fix report errors, and don't open new credit before you apply. When a paydown helps, a lender can request a rapid rescore so the new score shows in days.
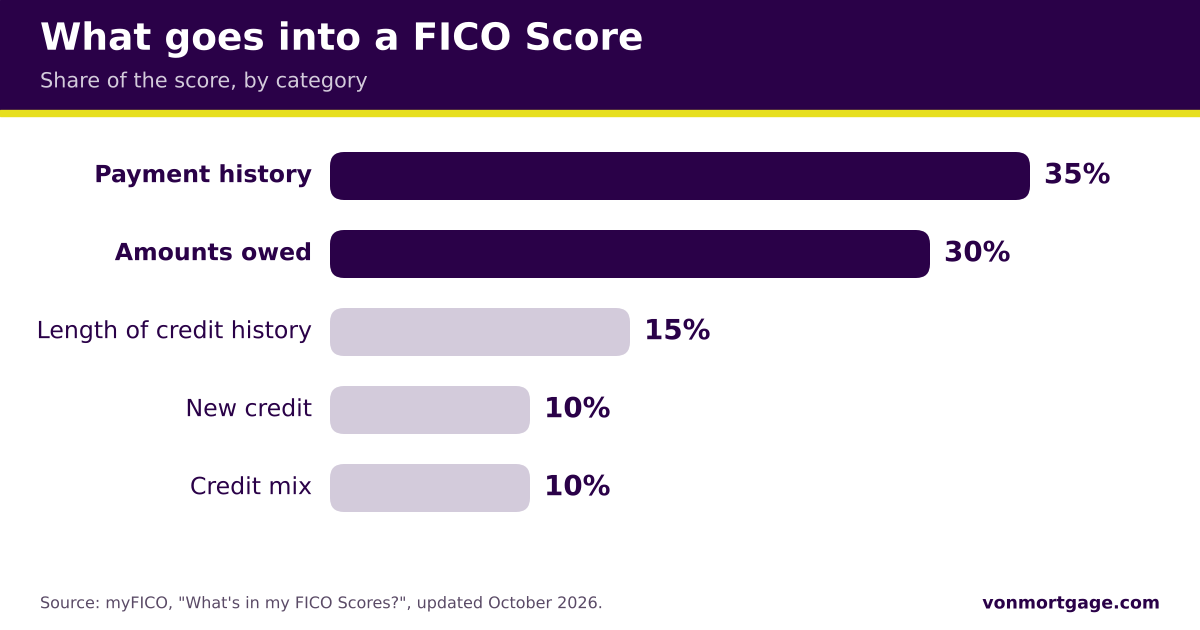
myFICO lists five parts of a FICO Score: payment history (35%), amounts owed (30%), length of credit history (15%), new credit (10%) and credit mix (10%). That comes from its page "What's in my FICO Scores?", updated October 2026.
My advice is simple. Live within your means. Pay your bills on time. Set up autopay on your credit cards, so a busy month never turns into a late payment.
How can you raise your mortgage credit score fast?
Lower the card balances that get reported, and do it before your statement closes. Experian (October 9, 2025) says many scoring models only look at your most recently reported balances and limits.
Utilization means how much of your card limit you are using. Experian says a good utilization rate is a low one, "ideally in the single digits." It also says 30% is the point where the harm to a score gets stronger.
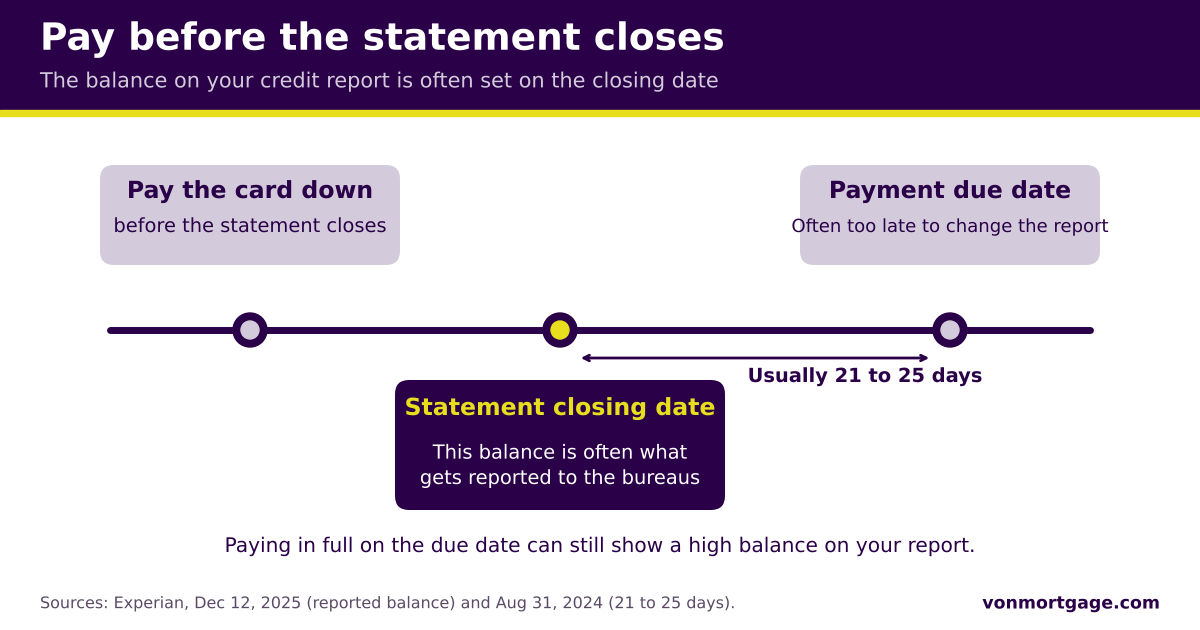
Timing matters too. Experian (December 12, 2025) says the balance on your credit report is often what you owed on the day your statement closed. Your due date usually comes 21 to 25 days after that (Experian, August 31, 2024). So if you pay in full on the due date, your report can still show a high balance. Pay the card down before the statement closing date.
You can also ask your card company for a higher limit. With the same balance and a bigger limit, your utilization goes down. If no bank will approve you for a card, a secured card is a way to start.
How much will paying down credit cards raise your score?
It depends on your credit file, and nobody can promise a number. Two families can pay off the same card balance and see different results.
Before you move any money, I run a what-if simulator on your credit report. It shows what your score would likely do if you paid a certain card down to a certain balance.
Sometimes the simulator shows that a small balance scores better than zero. myFICO's page on amounts owed (checked November 14, 2026) says that in some cases a low utilization ratio helps a FICO Score more than not using any of your credit at all. So talk to me before you zero out every card.
Does a rapid rescore really work, and how long does it take?
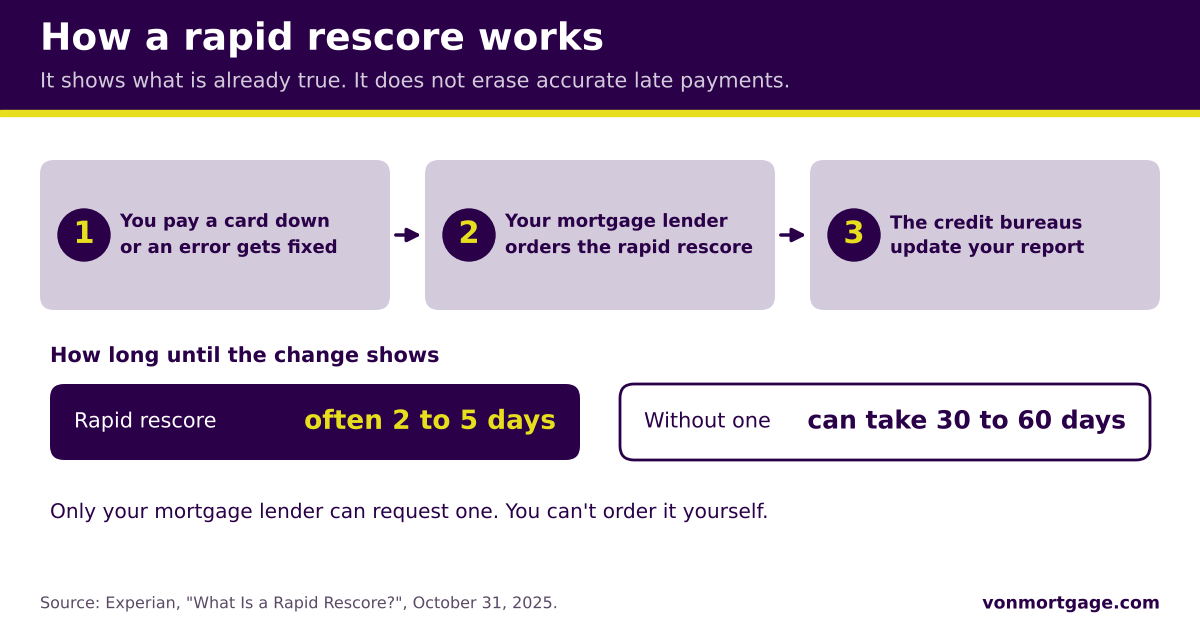
Yes, it works when there is something new and true to report, and it usually takes a few days. A rapid rescore is a fast update to your credit report that a mortgage lender orders from the credit bureaus.
Experian (October 31, 2025) says creditors can take 30 to 60 days to report a change on their own. It says a rapid rescore is often finished within two to five days once it's sent in. You can't order one yourself. Experian says only your mortgage lender can request it, and the lender isn't allowed to pass the fee straight to you, though Experian notes the cost can still show up in other closing costs.
When my office orders one, the update goes to all three bureaus.
A rapid rescore only shows what is already true, like a card you paid down or an error that got fixed. It doesn't erase accurate late payments. The CFPB (last reviewed September 2, 2026) says negative payment history can generally stay on a credit report for up to seven years.
What should you avoid doing to your credit before you apply for a mortgage?
Avoid anything that adds new debt or changes your accounts. That means:
- Opening a new credit card or store card
- Financing a car, furniture or appliances
- Closing old accounts
- Moving big balances from one card to another
- Missing a payment, even a small one
myFICO counts new credit as 10% of a FICO Score and length of credit history as 15%. Payment history is the biggest part at 35%, so a late payment hurts where it counts most. If you need to do one of these things, reach out first.
How do you fix errors on your credit report?
Get your free credit reports, then dispute the error in writing with both the credit bureau and the company that reported it. You can check your report from each of the three bureaus for free every week at AnnualCreditReport.com. Checking your own report doesn't affect your scores.
The CFPB (last reviewed September 2, 2026) says fixing an error generally means contacting both the credit reporting company and the company that gave it the information. Explain the problem in writing and include copies of the papers that back you up. The CFPB says the company that reported the information generally has to investigate and respond within 30 days.
Once an error is corrected, a rapid rescore can get the fix onto your report faster.
How do you improve your credit score to buy a house in Redding, California?
Start with a soft pull at our office, before you shop for a home. A soft pull lets me see your credit without a hard inquiry. Then I run the what-if simulator and give you a short list: which card to pay, down to what balance, and by what date. If a rapid rescore makes sense, my office orders it.
The score on your phone app may not match the one I see. myFICO (checked November 14, 2026) says mortgage lenders typically use FICO Score 5, FICO Score 4 and FICO Score 2. FHFA's credit scores page (updated October 2, 2026) says lenders can also use VantageScore 4.0 on loans sold to Fannie Mae and Freddie Mac.
If you want to know the credit score you need for a mortgage, that post covers it by loan type. Buying your first home? Our first-time homebuyer page shows where to begin.
What else do families ask about improving credit for a mortgage?
Families mostly ask how long it takes, whether to pay off collections, and whether a credit check will hurt.
How long does it take to improve your credit score for a mortgage?
It can take a few days or it can take months, depending on what needs to change. A card paydown can show within days with a rapid rescore. Without one, Experian (October 31, 2025) says creditors can take 30 to 60 days to report it. Late payments take longer to recover from.
Does paying off collections raise your credit score?
Not always. Don't pay a collection or give the company any money unless they agree to completely delete the account from the credit bureaus. Often the collector just updates the balance to zero, which can actually hurt the score. So talk to me before you pay one. Our credit page explains more.
Will checking my credit hurt my score before a mortgage?
Checking your own credit report does not hurt your score. A lender's hard pull can cost a little. myFICO (checked November 14, 2026) says one more inquiry usually takes less than five points off a FICO Score. It also says mortgage inquiries made close together count as one, in a window of 14 to 45 days depending on the score version. FICO Scores also ignore mortgage inquiries made in the 30 days before the score is figured. Keeping your rate shopping inside 14 days is the safe play. More in our post on whether a pre-approval hurts your credit.
What is the most common credit fix you see before a family buys?
The most common credit fix I see is paying down credit cards and getting the balances lower. If someone has a maxed-out card, paying it down can potentially move a score 20, 30, even 40 points. That's the range I see most, and utilization is the quickest lever there is. The other common fix is getting collections removed.
What should you do first if your credit score needs work?
Start with a soft pull, before you pay anything off or open anything new. Send me your info and I'll run the what-if simulator on your file. A blog post can't cover every situation. If yours doesn't fit what's here, reach out to Pete Metz, mortgage broker at Von Mortgage, NMLS #260571, and we'll look at it together.
Disclaimer: This information is educational and is not a commitment to lend, a loan approval, or an offer of credit. Any rates, payments, down payments or other figures shown are illustrative examples only, not quoted terms and not an offer to extend credit. Actual rates and terms depend on credit, income, property, occupancy and market conditions, and change daily. For current pricing see vonmortgage.com/rates.
Pete Metz NMLS #260571
Dream Big Ownership LLC dba Von Mortgage Company NMLS #2592815
CA CFL license 60DBO-195824
(530) 221-7700 · 2777 Bechelli Lane, Redding, CA 96002
Equal Housing Opportunity.
 Equal Housing Opportunity
Join the conversation
Comments are reviewed before they appear. Have a question about your own situation? Ask Pete directly — that stays private.
No comments yet