Recent Posts
Categories
Tags
Years
Does Mortgage Pre-Approval Hurt Your Credit or Lock You In?
Updated October 2026
No, and no. Most people treat a mortgage application like the credit card offer at a department store register. You apply, you get a yes or a no, and the no stings. So they put it off. A pre-approval works the opposite way, and the people who wait are usually the ones who would have gained the most from coming in early.
A pre-approval is the first look at your whole financial picture. What I do with that picture matters more than the letter it produces.
Does a soft credit pull for pre-approval affect your score?
No. A soft credit check does not affect your score in any way. At Von Mortgage we can start your pre-approval with a soft pull and issue the pre-approval letter from it. A hard pull only comes later, once you're ready to move forward on a home.
Starting soft is the smart move for almost everyone. Sometimes a pre-approval is just getting you the information you're after.
What if a lender does a hard pull, or you shop several lenders?
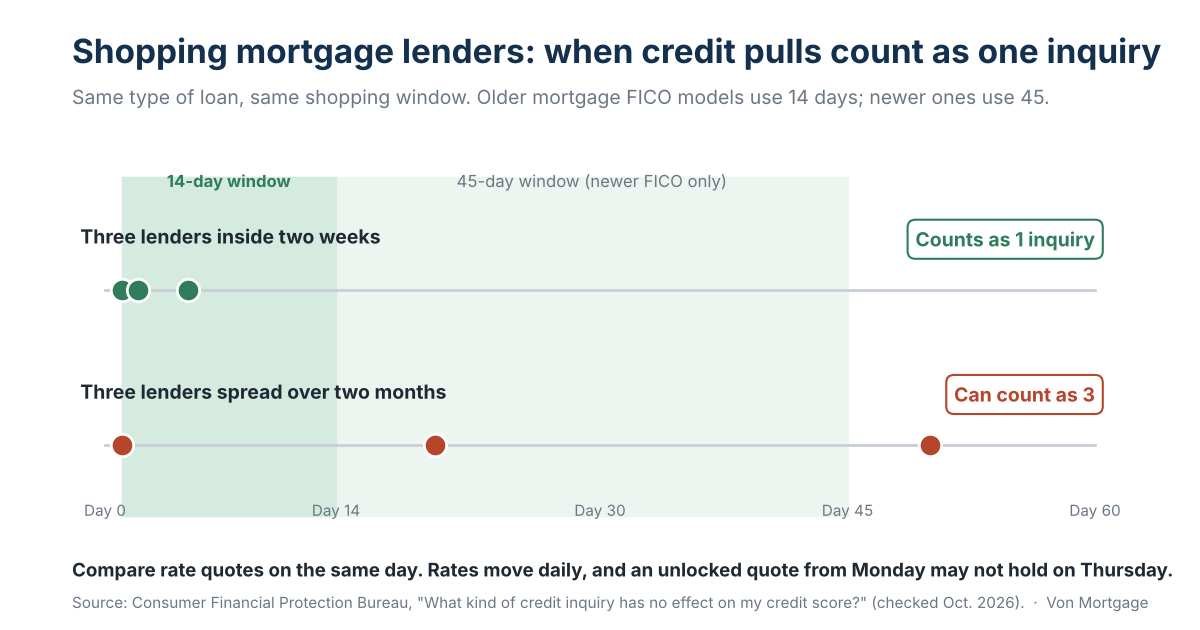
Shopping won't stack up against you. The Consumer Financial Protection Bureau says a single inquiry has little impact on your score, and that inquiries for the same type of loan within 14 to 45 days of each other count as no more than one (CFPB, checked October 2026).
The window depends on the scoring model. Newer FICO versions use 45 days. The older FICO versions most mortgage lenders still use treat 14 days as the window. If you're comparing lenders, get all your quotes inside two weeks and you're covered either way.
For comparing prices, two weeks is still too long. Get your quotes on the same day, as close together as you can. Rates move up and down with the market every day. A quote from Monday may not be valid on Thursday unless it was locked, and then you're comparing two different markets instead of two lenders.
The CFPB also notes that the most common scoring models ignore mortgage inquiries from the 30 days before your score is calculated. Shopping across two separate kinds of loans, like a mortgage and a car, counts as separate inquiries.
Will other lenders start calling you after your credit is pulled?
Far less than they used to. For years, a mortgage credit pull triggered a flood of calls and texts from lenders the borrower never contacted. The credit bureaus sold those "trigger leads."
The Homebuyers Privacy Protection Act, signed September 5, 2025 and in effect since March 5, 2026, amended the Fair Credit Reporting Act to restrict that practice. A lender can now only get a trigger lead if you already have a relationship with them or you opt in (National Mortgage Professional, March 5, 2026).
Does getting pre-approved tie you to that lender?
No. A pre-approval is not a contract. You can walk away at any point, and you can get a second opinion. I recommend you do.
Lenders pay for the credit report every time someone applies. A mortgage credit report runs $100 to $200 or more per pull. Some lenders pass that cost to you, and some absorb it. If you're shopping, each lender who pulls your credit is paying that just to give you a second opinion.
We are one of the lenders that don't charge for it, soft pull or hard pull. It's a cost of doing business. Whether you close with us or not, there's no obligation.
What do you actually get from a pre-approval?
You get three answers: how much you qualify for, which loan programs fit you, and what the total cost would be. You also get the letter you'll need when you write an offer.
The minimum score is lower than most people think. FHA allows scores as low as 500 with at least 10% down, and 580 or higher with 3.5% down, under HUD Handbook 4000.1. That's the program floor. What fits your file depends on your down payment and the rest of the picture. Our credit score requirements breakdown covers each program, and our first-time homebuyer page walks through the options.
Why should you get pre-approved before your credit is "ready"?
Because getting your credit ready is part of what we do. Once I can see the whole picture, I analyze the credit and help you raise the score before you pull the trigger on a home. Sometimes that means paying down a specific card. Sometimes it means getting on a three-way call with a collection agency to get a collection deleted.
Someone can get pre-approved as they are today. My job is to make sure they get the best deal possible, and a higher score usually means a better rate.
What a pre-approval doesn't do
A pre-approval is not final loan approval. The home still has to appraise, and underwriting still verifies everything when you're in contract. If your income, debts or credit change between the letter and closing, the approval can change with them. And if your rate shopping stretches past the scoring window, those inquiries can start counting separately.
What does this mean for you?
Don't wait for your credit to be perfect before you talk to a lender. Start with a soft pull, get the real numbers, and get a plan for the score. Then shop a second lender inside two weeks if you want to compare.
I'm Pete Metz, a mortgage broker at Von Mortgage in Redding, California (NMLS #260571). I've funded thousands of loans since 2003, and I never expect a client to work with me. If I help enough people get what they need, it takes care of itself. You can see our current rates live on the site, or start a pre-approval with a soft pull and see where you stand.
Disclaimer: This information is educational and is not a commitment to lend, a loan approval, or an offer of credit. Any rates, payments, down payments or other figures shown are illustrative examples only — not quoted terms and not an offer to extend credit. Actual rates and terms depend on credit, income, property, occupancy and market conditions, and change daily. For current pricing see vonmortgage.com/rates.
Pete Metz, Mortgage Broker · NMLS #260571
Dream Big Ownership LLC dba Von Mortgage · NMLS #2592815
2777 Bechelli Lane, Redding, CA 96002 · Pete@VonMortgage.com
Equal Housing Opportunity.
 Equal Housing Opportunity
Join the conversation
Comments are reviewed before they appear. Have a question about your own situation? Ask Pete directly — that stays private.
No comments yet