Recent Posts
Categories
Tags
Years
Many families who want a first rental hear the same thing: you need to be an experienced investor to get a DSCR loan. A first-time investor doesn't. This guide explains how a DSCR loan works for a first rental, what to expect, and what to know before you make an offer in Redding, California.
Can a first-time investor get a DSCR loan?
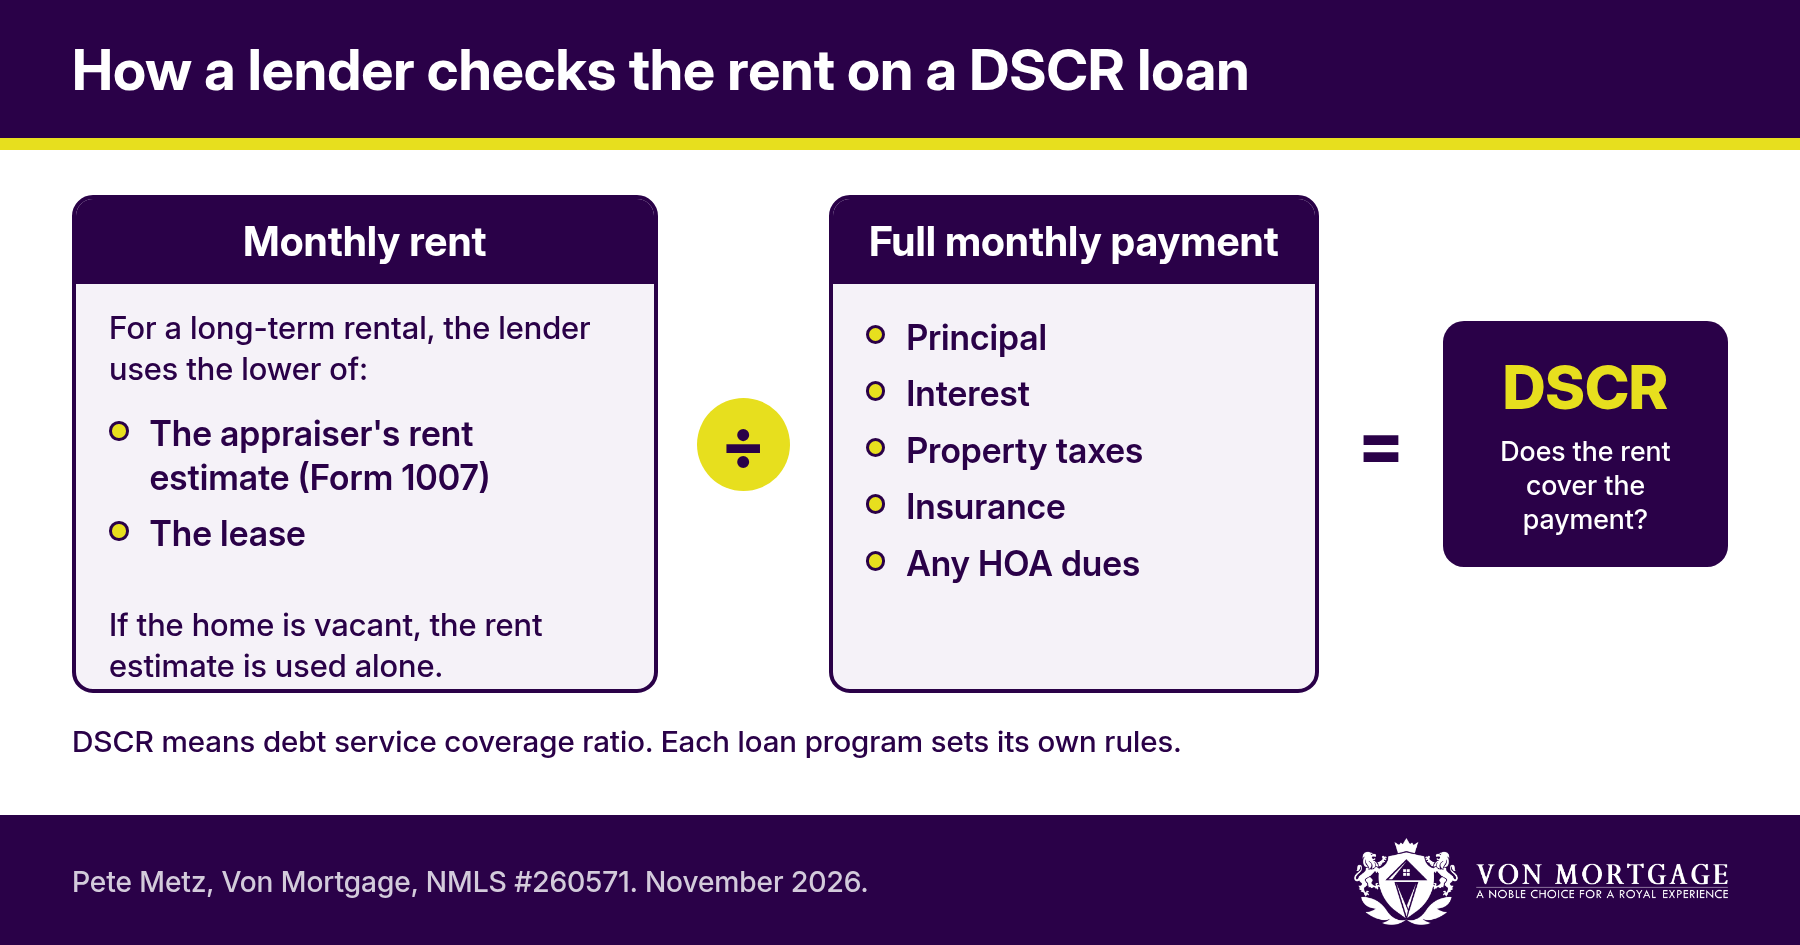
Yes. A first-time investor can qualify for a DSCR loan on the rental's income instead of tax returns, as long as the home is truly an investment. Expect a larger down payment and pricier terms than an experienced investor gets. The lender divides the monthly rent by the full payment, including taxes, insurance and any HOA dues.
DSCR stands for debt service coverage ratio. That is a long name for a simple check: does the rent cover the payment?
A regular home loan is built around your paycheck. A DSCR loan is built around the rental. That is why a first-time investor can still use it, even without a track record as a landlord.
Can you get a DSCR loan with no experience?
Yes. We don't ask for a real estate experience letter. We just confirm you own a home now, and that shows right on your application.
The one thing that has to be true is that the property is a real investment. You are buying it to rent out, not to live in. You will sign a form that says so.
If you don't own a home today, tell me up front. Some loan programs don't allow that, and others do.
Being new does cost something. A first-time investor should expect a bigger down payment and more expensive terms. I'd rather you hear that from me before you start shopping.
What do you need for a first rental property loan?
You need a down payment, credit that fits the loan, a plan for reserves, and a rent number the lender can document. Here is what each one means:
- Down payment: First-time investors should expect to put more down than an experienced investor.
- Credit: The lender checks your credit report, and the loan program sets what it needs.
- Reserves: These are savings you still have after closing. Rules vary by loan program. Some require reserves and some don't. No reserves usually means a higher rate or cost.
- Rent: The rent is what carries the file, so the lender needs a documented number.
The exact list changes from one loan program to the next. For the full paperwork list, see the documents a DSCR loan needs.
How does the rent cover the payment on a first rental property?
The lender divides the monthly rent by the full monthly payment, which includes principal, interest, taxes, insurance and any HOA dues. The more the rent covers the payment, the stronger the file looks. Each loan program sets its own rules for how much it needs.
How the rent is counted depends on how you plan to rent the home. There are three kinds of rentals:
- Long-term: A tenant on a regular lease.
- Mid-term: Stays of 30 days or more.
- Short-term: Nightly or weekly stays, like an Airbnb.
For a long-term rental, the lender uses the lower of two numbers: the appraiser's rent estimate (called the 1007) or the lease. If the home is vacant, it uses the appraiser's rent estimate alone. Mid-term and short-term rentals are counted a different way. We cover that in our guide to a short-term rental DSCR loan.
You can also get a rough idea of how much a home could rent for on your own.
What can go wrong with a DSCR loan on your first rental?
The rent number is the usual weak spot. If there is no lease in place, the rent number doesn't come until the appraisal is back, about a week into escrow. The appraisal can bring surprises, so nobody knows the final number until then.
No single document holds up a DSCR file. The rent calculation does. That is why it helps to work with a lender who researches the rent before you make an offer.
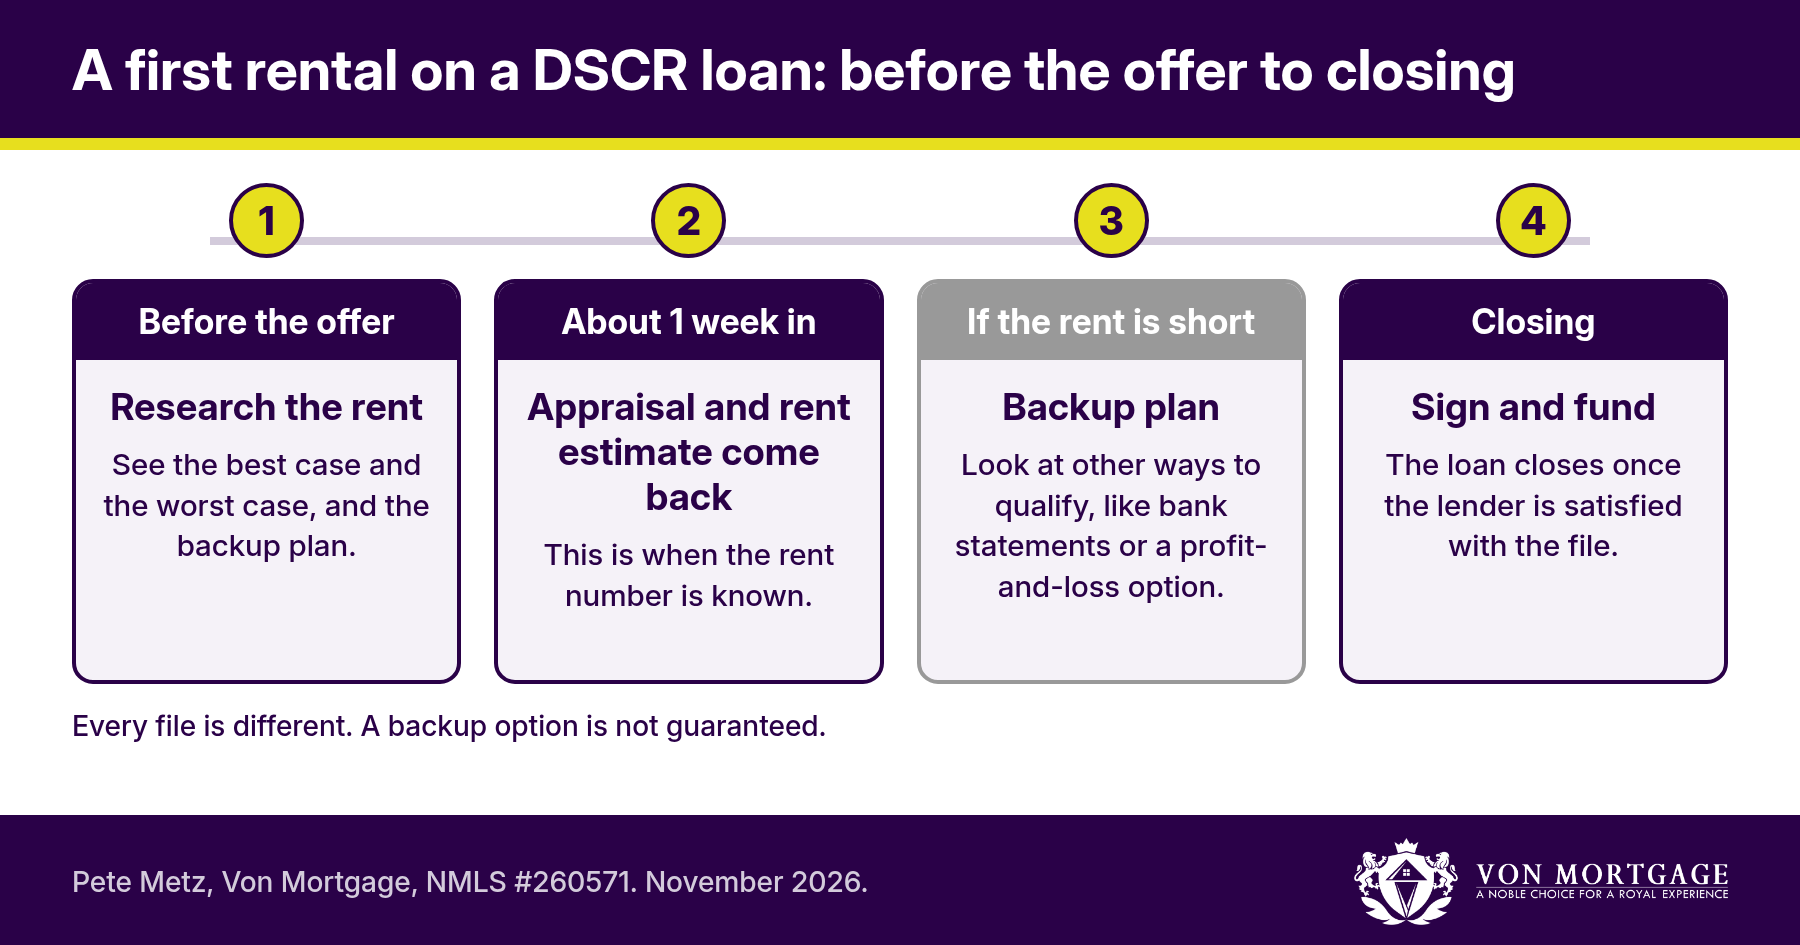
It also helps to have a backup plan. If the rent comes in short, we look at other ways to qualify, like bank statements or a profit-and-loss option. There isn't one automatic answer, and a backup option is not guaranteed. But knowing about it early beats finding out in escrow.
What should a first-time investor in Redding, California know before writing an offer?
Know your best case and your worst case before you sign. Here is what I'd do before writing an offer on a first rental:
- Ask your lender to research the rent first, so the rent number isn't a surprise.
- Decide how you will rent the home: long-term, mid-term or short-term.
- Plan for a bigger down payment and pricier terms on your first one.
- Ask how reserves work for the loan program you are looking at.
- Have a backup plan in case the rent comes in short.
If you are planning a mid-term or short-term rental, or your situation is different, reach out. We'll look at it with you.
Still looking for the property? You can search homes for sale. When you find one, send me the address and the rent you expect. I'll show you the best and worst cases before you write the offer.
Written November 2026 by Pete Metz, NMLS #260571. Von Mortgage is a mortgage broker in Redding, California. We work with families in California, Oregon, Washington, Indiana, Texas, Louisiana and Florida.
What else do families ask about a DSCR loan for a first rental?
How does a DSCR loan work for a first-time investor?
A DSCR loan qualifies you on the rental's income instead of your tax returns. The lender divides the monthly rent by the full monthly payment, including taxes, insurance and any HOA dues. A first-time investor goes through the same check, with a bigger down payment and pricier terms. See our DSCR investor loans page for program details.
Do you need landlord experience for a DSCR loan?
No. At Von Mortgage we don't ask for a real estate experience letter. We confirm that you own a home now, which shows on the application. The rental has to be a true investment property.
Can you use a DSCR loan for your first rental property?
Yes. A DSCR loan can finance your first rental property if it is truly an investment. Expect a larger down payment and pricier terms than an experienced investor gets. Different loan programs have different rules, so reach out and we'll look at your file.
Disclaimer: This information is educational and is not a commitment to lend, a loan approval, or an offer of credit. Any rates, payments, down payments or other figures shown are illustrative examples only, not quoted terms and not an offer to extend credit. Actual rates and terms depend on credit, income, property, occupancy and market conditions, and change daily. For current pricing see vonmortgage.com/rates.
Pete Metz, Mortgage Broker · NMLS #260571
Dream Big Ownership LLC dba Von Mortgage Company · NMLS #2592815
Loans made or arranged pursuant to a California Financing Law license, #60DBO-195824.
2777 Bechelli Lane, Redding, CA 96002 · (530) 221-7700 · Pete@VonMortgage.com
Equal Housing Opportunity.
 Equal Housing Opportunity
Join the conversation
Comments are reviewed before they appear. Have a question about your own situation? Ask Pete directly — that stays private.
No comments yet