Recent Posts
Categories
Tags
Years
How Much Money Do You Need to Close on a House in California?
You need more than your down payment. You need the down payment, your closing costs, a deposit and an appraisal fee paid weeks before closing, and a set of prepaid taxes and insurance that almost no one expects. A seller credit can cover most of that, which is the part buyers don't know to ask for.
That prepaid piece is the one I spend the most time explaining. Prepaids aren't a cost of the loan. They're your own money, set aside in advance to pay your own bills.
I'm Pete Metz, a mortgage broker at Von Mortgage in Redding, California (NMLS #260571). Below is every dollar a buyer brings, in the order it leaves their account, with a worked Shasta County example. After that is the number I think matters more than any of it. *Updated October 2026.*
What do you pay before closing day?
Three things come out of your account during escrow, before you ever sit down to sign.
The earnest money deposit. This usually runs 1% to 5% of the purchase price. Under the standard California purchase contract (C.A.R. Residential Purchase Agreement, revised December 2022), it's due into escrow within three business days after the seller accepts your offer. It isn't a fee. At closing it's credited toward your down payment or closing costs. It's there to show the seller you're serious, and you can lose it if you walk away after your contingencies are released.
The appraisal. The lender needs an appraisal before it will fund the loan, and you want one too, because it tells you whether the price holds up. The appraiser wants to be paid before going out to the property. In our market that runs $600 and up, depending on the size, location and complexity of the home. Investment properties cost more, because the appraiser adds Fannie Mae Form 1007, a rent schedule that estimates what the property would rent for.
The home inspection. The lender doesn't require one. Get one anyway. Inspections run $350 to $600 or more depending on the size of the home, and the report is what you use to ask for repairs, a price cut or a seller credit. Those are usually worth far more than the inspection, and most of our buyers get the cost back that way. Roof, pest, pool, heating and air, and foundation inspections are all optional and often worth it. On most stick-built homes, the appraisal is the only inspection the lender requires.
What do you bring to the closing table?
Your down payment, plus closing costs, plus prepaids, minus the earnest money you already deposited and any credit the seller gives you toward your costs.
Closing costs are the price of the loan and the transaction: lender fees, title insurance, escrow and recording. In our files, closing costs and prepaids together usually run about 3% to 4% of the purchase price, depending mostly on whether points are being paid. Prepaids are the part that surprises people.
What are prepaids, and why do you pay them up front?
Prepaids are your own housing bills, paid in advance. Most buyers want their taxes and insurance included in the monthly payment. What they don't know is that setting that up means funding an account at closing.
Insurance comes first. The first 12 months of your homeowner's policy are always paid at closing, whether or not you include insurance in your payment. If you do include it, the lender also collects two to three more months to start the account.
Insurance is the wild card in California. The premium on one house can be several times the premium on another a mile away, and it's the line that moves your cash to close and your payment the most. If you're buying in California, get an insurance quote on the address well before you have an accepted offer. Our guide to fire insurance in Shasta County covers who is writing policies and what they cost.
Taxes come next. The lender collects enough months of property tax so the account can pay your next bill on time. How many months depends on when you close, because Shasta County bills taxes in two installments, late after December 10 and April 10, according to the Shasta County Tax Collector. Federal rules let the lender hold a cushion of up to one-sixth of a year's taxes and insurance, about two months, on top of what the next bills require (CFPB, 12 CFR 1024.17).
Interest is last. You prepay daily interest from your closing date to the end of that month.
All of that becomes an escrow account, which is your reserve money. The lender pays your tax and insurance bills from it. If the yearly review finds more than $50 over what's needed, the lender has to refund it (12 CFR 1024.17(f)).
One bill isn't in your cash to close. California sends new owners a supplemental property tax bill a few months after closing, and it goes to you, not your lender. Our Shasta County property tax guide shows how to estimate it.
What does it look like on a $400,000 home in Redding?
Here's an example, an FHA purchase at 3.5% down, closing mid-month.
| Item | When it's paid | Amount |
|---|---|---|
| Earnest money (1%) | Within 3 business days | $4,000 |
| Appraisal | First week of escrow | $600 |
| Home inspection | Inspection period | $450 |
| Down payment (3.5%) | Closing | $14,000 |
| Lender, title and escrow fees | Closing | $7,400 to $11,400 |
| Homeowner's insurance, first 12 months | Closing | $1,800 |
| Insurance reserve, 3 months | Closing | $450 |
| Property tax reserve, 3 months | Closing | $1,089 |
| Prepaid interest, 16 days | Closing | $1,274 |
| Earnest money already deposited | Credited at closing | −$4,000 |
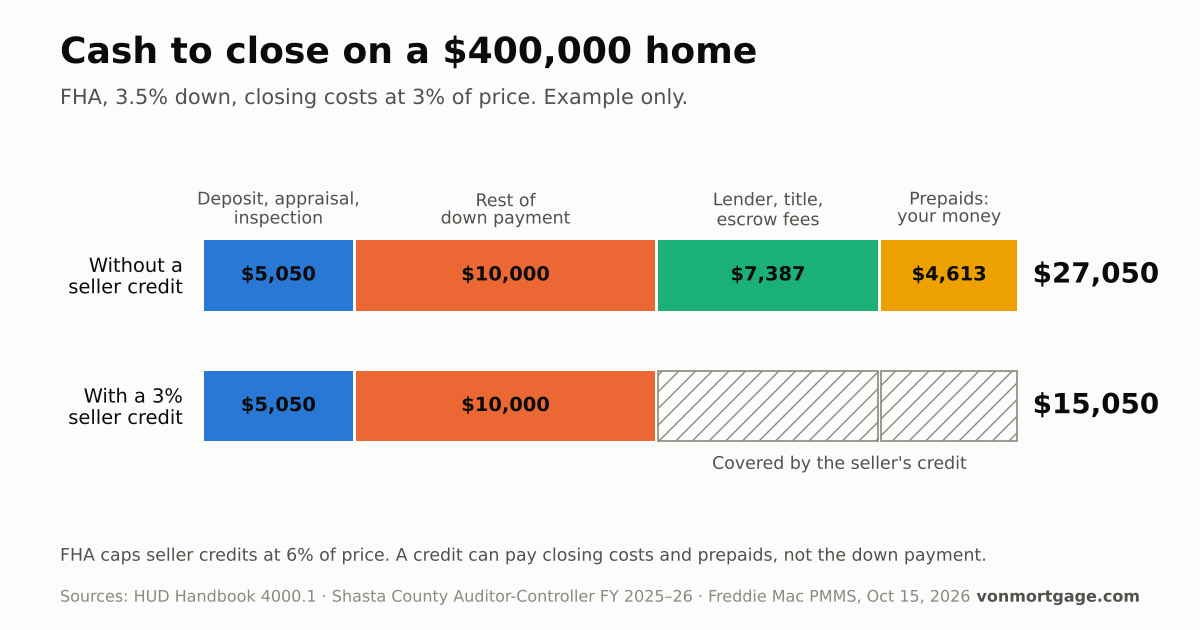
Closing costs and prepaids together come to $12,000 to $16,000, which is 3% to 4% of the price. All in, this buyer brings roughly $27,000 to $31,000. Of that, $4,613 is prepaids: your own tax, insurance and interest money, paid ahead.
The assumptions behind the example: FHA's 3.5% minimum down payment (HUD Handbook 4000.1), with the 1.75% upfront mortgage insurance premium financed into a $392,755 loan. The 7.40% rate is Freddie Mac's Primary Mortgage Market Survey average for the week of October 15, 2026, used for illustration. Taxes are $4,357 a year in the Enterprise school district, from the Shasta County Auditor-Controller's 2025–26 rates. Insurance is $1,800 a year, inside the $900 to $2,000 range we see on a small home inside city limits (September 2026). A home in a high fire zone can cost several times that.
Can the seller pay your closing costs?
Yes. A seller credit can cover all of your loan's closing costs, and your prepaids too. You ask for it in your offer, or after the inspection in place of repairs. At closing, the seller's proceeds pay those costs instead of your cash.
Each loan program caps how much the seller can contribute:
| Loan type | Seller credit limit | Source |
|---|---|---|
| FHA | Up to 6% of the sales price | HUD Handbook 4000.1 |
| Conventional, under 10% down | Up to 3% | Fannie Mae Selling Guide B3-4.1-02 |
| Conventional, 10% to 25% down | Up to 6% | Fannie Mae Selling Guide B3-4.1-02 |
| Conventional, over 25% down | Up to 9% | Fannie Mae Selling Guide B3-4.1-02 |
| Conventional, investment property | Up to 2% | Fannie Mae Selling Guide B3-4.1-02 |
| VA | Normal closing costs, plus up to 4% in other concessions | VA Lenders Handbook, Chapter 8 |
Two rules matter. A credit can pay closing costs and prepaids, but not your down payment. And it can't be more than your actual costs. Any amount left over doesn't come back to you as cash.
In the $400,000 example, a 3% credit of $12,000 would cover the low end of the closing costs and all of the prepaids. FHA allows up to 6%, which is $24,000 on this home, so even the high end can be covered. What's left is $5,050 paid during escrow and $10,000 at closing, which is the rest of the down payment after your deposit. That's $15,050 instead of roughly $27,000 to $31,000.
Why is cash to close only half the question?
Because it tells you what the house costs this month, not what the loan costs over the time you'll have it.
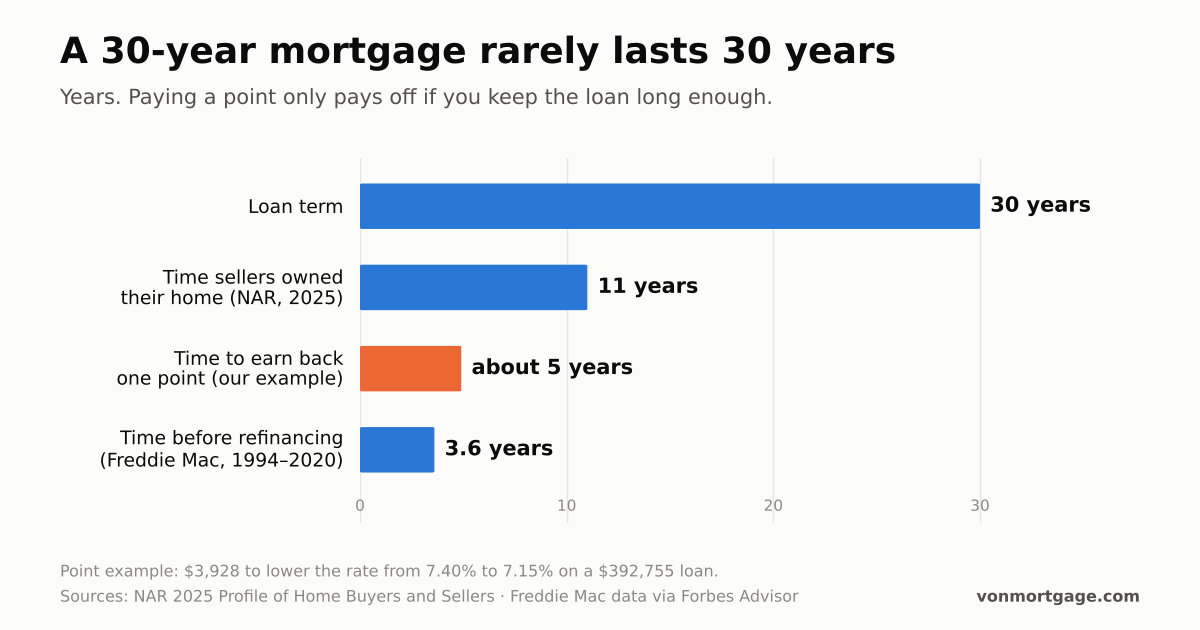
Most buyers assume a 30-year mortgage lasts 30 years. It almost never does. In the National Association of Realtors' 2025 Profile of Home Buyers and Sellers, sellers had owned their homes a median of 11 years, the longest on record. Freddie Mac data from 1994 through early 2020 put the median time before a borrower refinanced at 3.6 years (as reported by Forbes Advisor).
So we look at total cost over three windows: 3 to 5 years, 10 to 15 years, and 25 to 30 years. The cheapest loan in one window is often the most expensive in another.
My advice is to avoid paying points if you can. To earn them back, you have to keep the loan for years, and most people don't.
Take one discount point, $3,928 on this loan, to lower the rate from 7.40% to 7.15%. That saves about $67 a month, so it takes about 59 months, almost five years, to break even. At the 3.6-year median before a refinance, you'd be about $1,060 behind. The savings only show up if you keep the loan well past five years.
Watch for this when you compare lenders. Many online retail lenders build one to three points into the quote they advertise. The rate looks low because you're paying for it up front. Check the Loan Estimate for "points" in Section A before you compare rates. Our post on paying points goes deeper.
The part that doesn't show up on your Loan Estimate
Saving money over 30 years usually means spending more in years 3 to 5. Points, buydowns and lower-rate options cost cash now and pay you back slowly. If you want the lowest cost for the first few years, you'll pay more over 30 years, if you keep the loan that long.
Nobody knows for sure which buyer they'll be. Rates may fall and you refinance. A job may move you. That's why I don't pick one answer for a client. I show the total cost in each window and let them choose with real numbers in front of them.
Your prepaids will also move. The tax reserve changes with your closing month, and the insurance number isn't real until you have a quote on the actual address.
A seller credit isn't free money. In a competitive market, asking for one can make your offer weaker than one that doesn't. Sometimes the seller agrees but wants a higher price to cover it, and the appraisal still has to support that price. If it comes in low, the gap is yours to cover or renegotiate.
What this means for you
Get every cost in writing before you write an offer. Get an insurance quote on the address before you write the offer too. Ask your agent whether a seller credit belongs in it. Keep cash for the deposit, appraisal and inspection ready in the first week of escrow. Treat prepaids as savings moved, not money spent. And check any quote for points before you compare rates.
Every buyer we work with on a first home purchase gets what we call a total cost analysis. It shows the out-of-pocket costs up front and what the mortgage costs over 3 to 5, 10 to 15 and 25 to 30 years, with options side by side. I'd rather you see the whole number before you write an offer than at the signing table. If you want yours, start with a quote and I'll run it on a real address.
Disclaimer: This information is educational and is not a commitment to lend, a loan approval, or an offer of credit. Any rates, payments, down payments or other figures shown are illustrative examples only — not quoted terms and not an offer to extend credit. Actual rates and terms depend on credit, income, property, occupancy and market conditions, and change daily. For current pricing see vonmortgage.com/rates.
Pete Metz, Mortgage Broker · NMLS #260571
Dream Big Ownership LLC dba Von Mortgage · NMLS #2592815
2777 Bechelli Lane, Redding, CA 96002 · Pete@VonMortgage.com
Equal Housing Opportunity.
 Equal Housing Opportunity
Join the conversation
Comments are reviewed before they appear. Have a question about your own situation? Ask Pete directly — that stays private.
No comments yet