Recent Posts
Categories
Tags
Years
Can You Use a VA Loan to Buy a Fourplex? What It Takes
Yes. A VA loan can buy a property with up to four units, a duplex, triplex or 4-plex, with no down payment, as long as you live in one of the units. Most veterans I talk to have no idea this is possible. They assume VA means a single-family house, and they never ask.
The rules change a little once you go past one unit. The rent from the other units can help you qualify, but VA attaches two conditions to it, and those conditions decide whether the deal works. Updated October 2026.
Can you buy a fourplex with a VA loan?
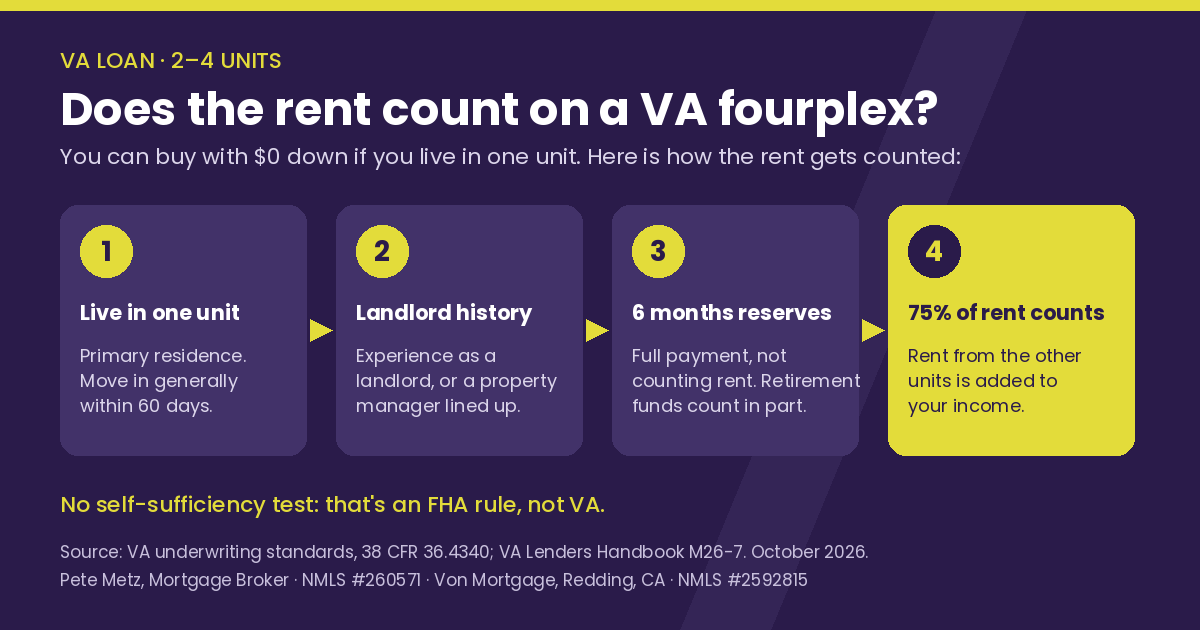
Yes, if it will be your primary residence. VA loans cover homes with one to four units. You have to move into one of the units, generally within 60 days of closing, under the VA Lenders Handbook (M26-7, Chapter 3). You can't buy a fourplex with a VA loan and rent out all four units from day one.
Do you need a down payment on a VA fourplex?
No. A veteran with full entitlement has no VA loan limit and can buy a fourplex with zero down, the same as a single-family home. You'll pay the VA funding fee: 2.15% of the loan on a first use with nothing down, and 3.3% on later uses, per the VA.gov funding fee chart (confirmed for 2026). Veterans receiving VA disability compensation are exempt. The fee can be rolled into the loan.
Does the rent from the other units count toward qualifying?
Yes, at 75% of the expected rent. If the other three units would rent for $4,200 a month combined, the lender counts $3,150 of it as income.
To use that rent at all, VA requires two things under its underwriting standards (38 CFR 36.4340):
- Landlord experience, or a property management company lined up to run the building.
- Six months of the full mortgage payment (principal, interest, taxes and insurance) in reserves, without counting the rent.
Can retirement accounts count toward the six months of reserves?
Yes. This is the part people miss. Reserves don't have to sit in a checking account. A 401(k), IRA or other retirement account can count. Lenders usually count only part of the vested balance, often around 60%, because of taxes and early-withdrawal penalties (Veterans United reserve guidance, 2026). A veteran who doesn't have $28,000 in the bank may still meet the requirement with a retirement account they never thought of as an asset.
What does that look like on a Redding fourplex?
The fourplexes I see in Redding sell for roughly $500,000 to $600,000. Here's an example in the middle of that range.
A veteran using VA for the first time buys a $550,000 fourplex with nothing down. The 2.15% funding fee is financed, so the loan is about $561,825. At 7.40%, the Freddie Mac Primary Mortgage Market Survey 30-year average for the week of October 15, 2026, principal and interest run about $3,890 a month. Add roughly $750 for taxes and insurance and the full payment is about $4,640.
Six months of reserves is about $27,840. If the lender counts 60% of a retirement account, that takes roughly $46,400 vested.
To price your own scenario, check today's rates.
Does VA require the rent to cover the whole mortgage?
No. That's an FHA rule. FHA applies a self-sufficiency test to three- and four-unit homes, where the rent has to cover the full payment. VA's underwriting standards don't include one. Several large VA websites get this wrong.
Why won't the rent carry the loan by itself?
Because your own income still has to do most of the work. A veteran asked me about buying a fourplex. The rents on the building looked good. His income wasn't there, and 75% of the rent wasn't enough to close the gap.
In the example above, $3,150 of counted rent against a $4,640 payment leaves about $1,490 a month for you to carry. That's on top of your car payment, cards and everything else. VA also tests residual income, the money left over each month after all your bills. A fourplex is a lot of payment.
You're also a landlord the day you move in. Three tenants, three sets of repairs, and vacancies that don't care about your schedule.
What should you do after you move out?
Live there, then use a DSCR loan for the next one. That's what I'd tell a veteran sitting across from me.
Once you've lived in the fourplex, you can move out and rent all four units. The VA loan stays in place. Your next investment property can go on a DSCR loan, which qualifies you on the property's rent instead of your personal income. The fourplex becomes your first rental, bought with no money down.
I'm Pete Metz, a mortgage broker at Von Mortgage in Redding, California, NMLS #260571. If you're a veteran looking at a duplex, triplex or fourplex, send me the listing. I'll run the real numbers on a VA loan and tell you whether the rent and your income get you there.
Disclaimer: This information is educational and is not a commitment to lend, a loan approval, or an offer of credit. Any rates, payments, down payments or other figures shown are illustrative examples only — not quoted terms and not an offer to extend credit. Actual rates and terms depend on credit, income, property, occupancy and market conditions, and change daily. For current pricing see vonmortgage.com/rates.
Pete Metz, Mortgage Broker · NMLS #260571
Dream Big Ownership LLC dba Von Mortgage · NMLS #2592815
2777 Bechelli Lane, Redding, CA 96002 · Pete@VonMortgage.com
Equal Housing Opportunity.
 Equal Housing Lender
Join the conversation
Comments are reviewed before they appear. Have a question about your own situation? Ask Pete directly — that stays private.
No comments yet